
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Lesson 5: 14.5: Latency Arbitrage & Cross-Venue Arbitrage
Study geographic price discrepancies across fragmented exchanges, SIP feed delays, and speed-based arbitrage.
1. Market Fragmentation & Price Discrepancies
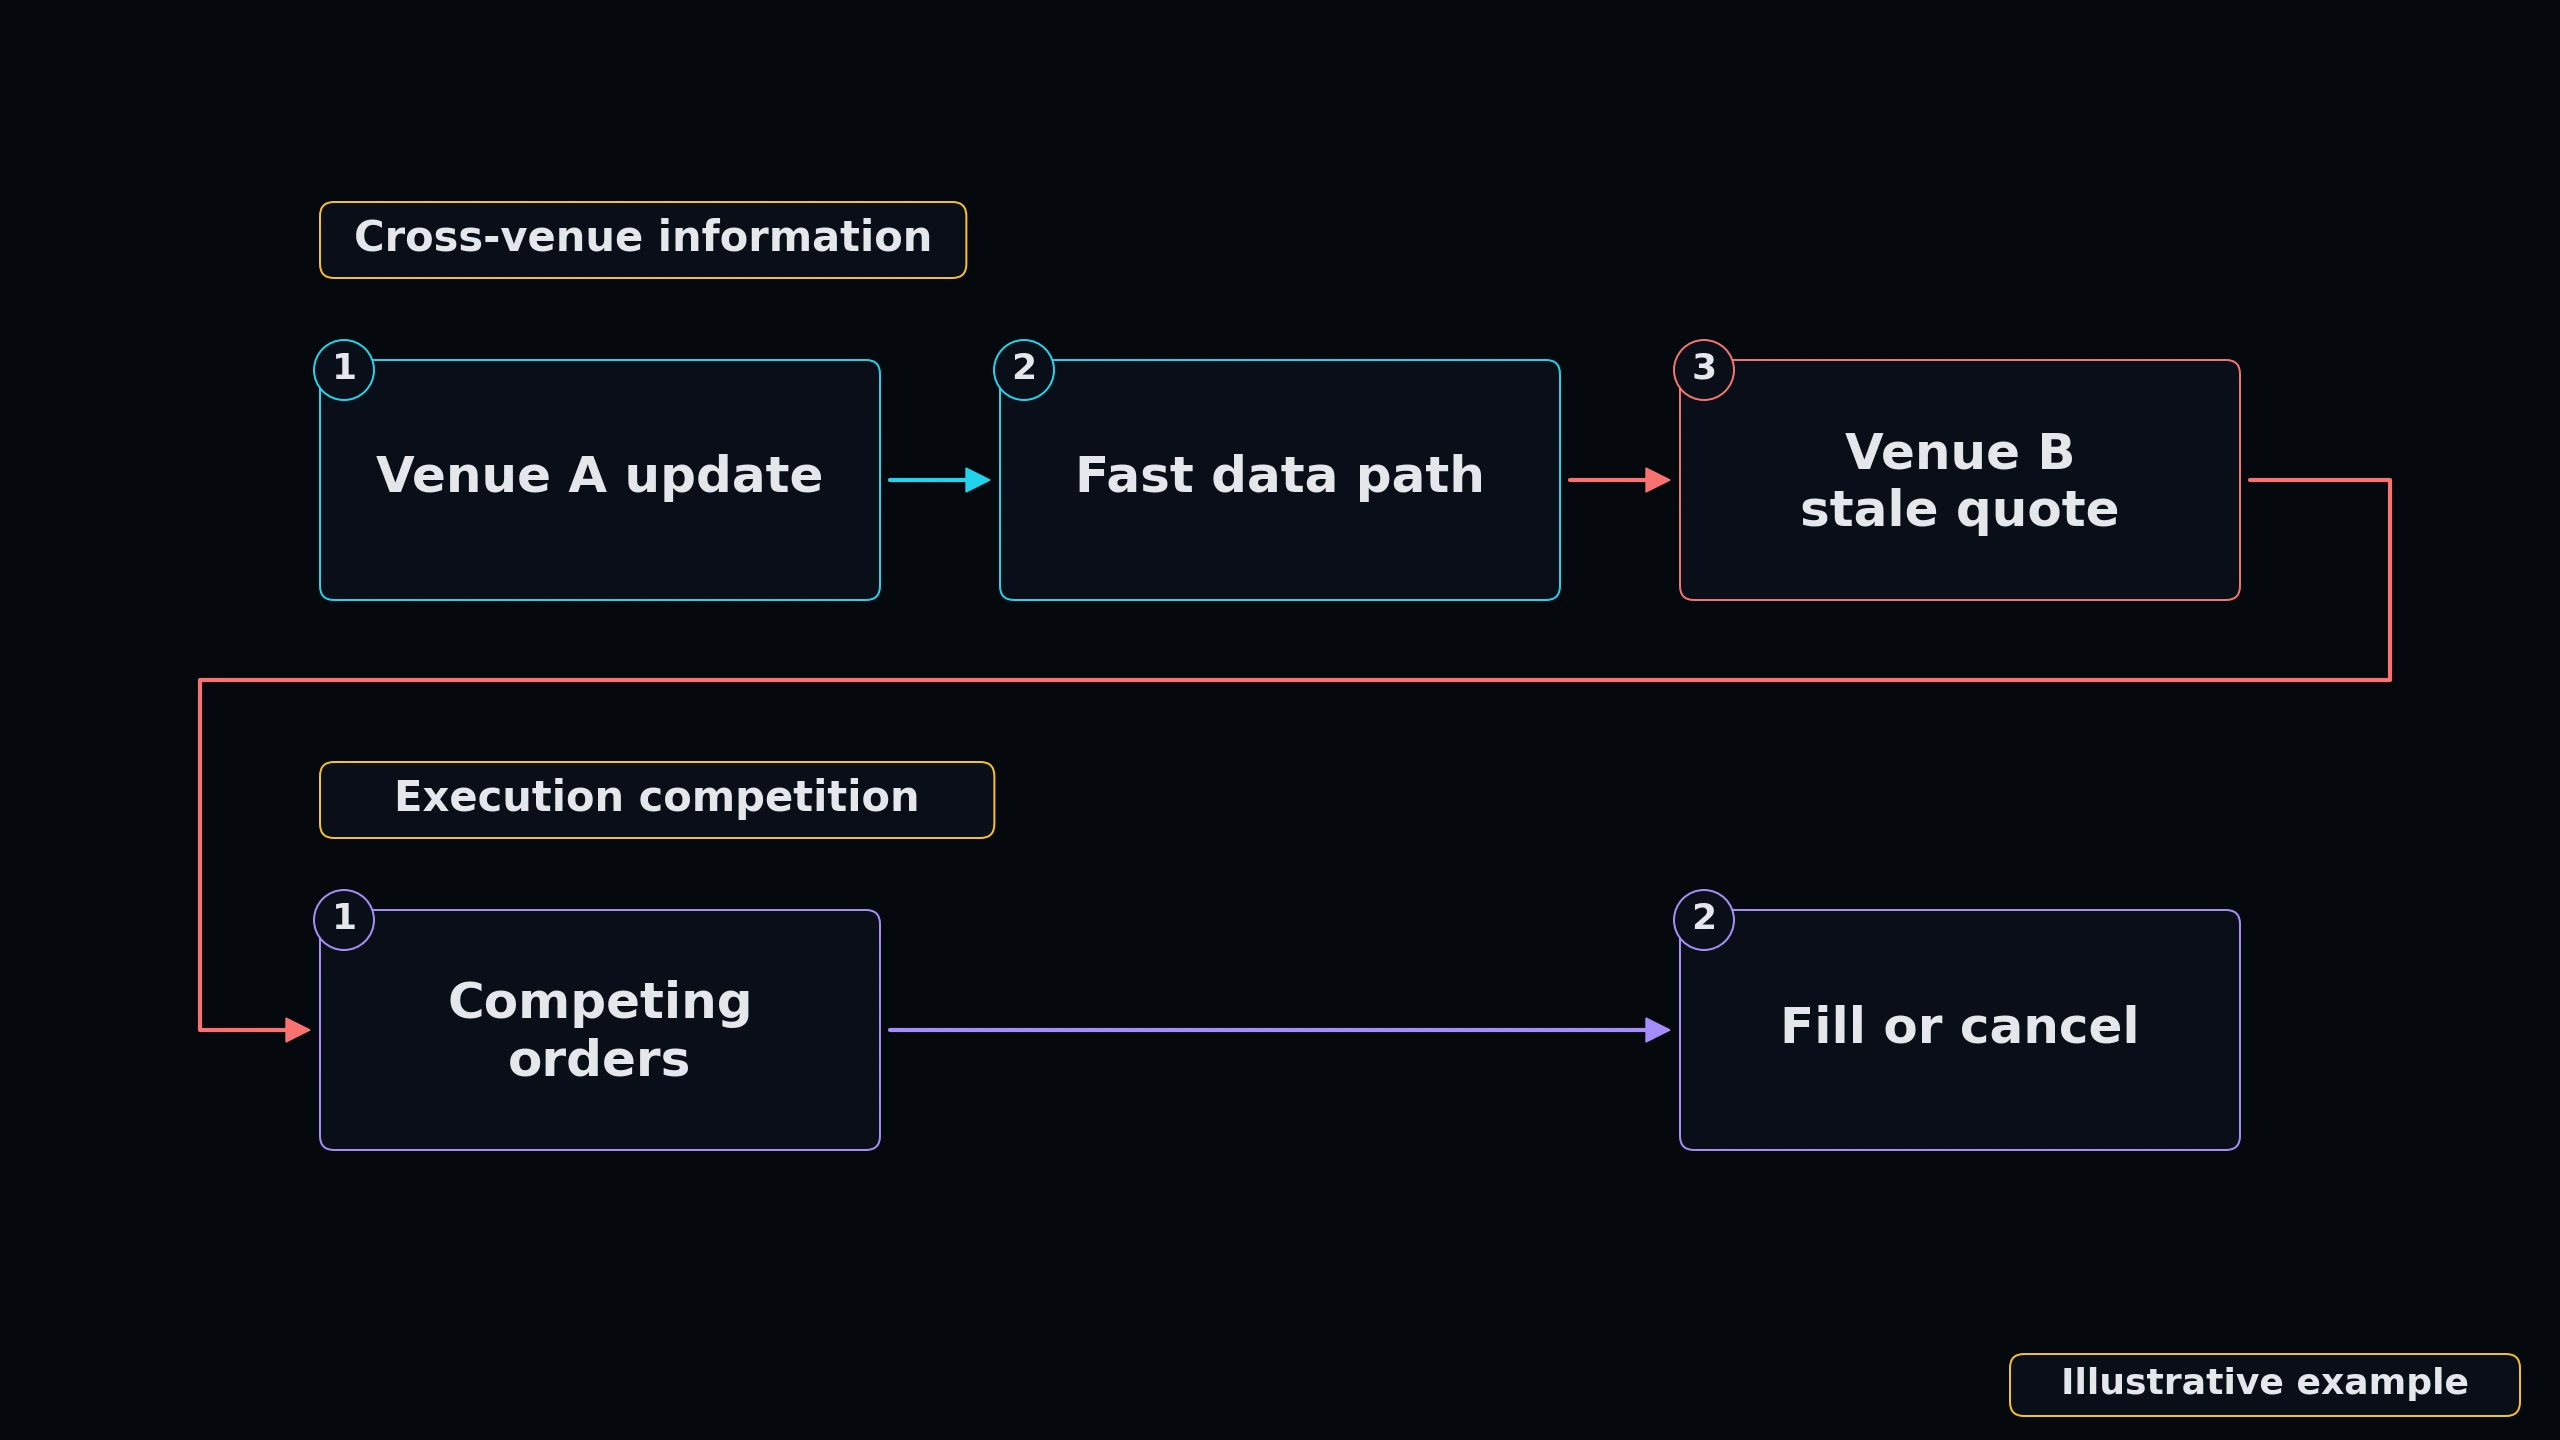
Modern equity markets are fragmented across multiple lit exchanges (e.g., NYSE, NASDAQ, BATS, EDGA). When a large order executes on NASDAQ and clears out the offer, the price on NYSE may briefly lag by several microseconds.
Latency arbitrageurs detect the trade on NASDAQ and use microwave links to sweep the lingering lower-priced offers on NYSE before slow institutional orders arrive.
★ SIP Feed Latency: The Securities Information Processor (SIP) aggregates quotes across all exchanges, but direct feeds arrive microseconds faster than the consolidated SIP feed.
2. Phantom Liquidity
When institutional traders attempt to buy shares across multiple venues simultaneously without smart routing, latency arbitrage causes quotes on destination venues to disappear before execution, creating 'phantom liquidity'.
 Click to enlarge
GEX Heatmap & Dealer Hedging Profile
The Gamma Exposure (GEX) profile dictates the hedging loops of market-makers. Slide the price pointer below to see how institutional hedging flows suppress volatility or trigger cascading market trends.
Price Controller
Gamma Transition Zone (Near $100): Resting near the Volatility Flip Line. Dealer hedging is transitioning, making the price range choppy as dealer flows oscillate. Expect choppy intraday price ranges.
KNOWLEDGE RECONNAISSANCE
What enables cross-venue latency arbitrage in fragmented stock markets?
More lessons in this module
- 14.0: Introduction to High-Frequency Trading (HFT)
- 14.1: Microsecond Hardware, FPGAs & Kernel Bypass
- 14.2: Exchange Matching Engines & Order Gateways
- 14.3: Co-Location & Microwave Transmission Networks
- 14.4: Market Making Algorithms & Inventory Risk
- 14.6: Dark Pools, Internalization & Payment for Order Flow (PFOF)
- 14.7: HFT Risk Controls, Circuit Breakers & Kill Switches
- 14.8: Analyzing HFT Impact on Market Quality & Liquidity
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.