
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Lesson 0: 17.0: Modern Portfolio Theory (MPT) & Efficient Frontier Optimization
Master Markowitz mean-variance optimization, variance-covariance matrices, efficient frontiers, and Sharpe ratio maximization.
1. Markowitz Mean-Variance Optimization Framework
Pioneered by Harry Markowitz, Modern Portfolio Theory (MPT) provides a mathematical framework for constructing portfolios that maximize expected return for a given level of risk.
Portfolio variance depends not only on individual asset variances but crucially on pairwise asset covariances: σ_p² = Σ Σ w_i w_j σ_ij.
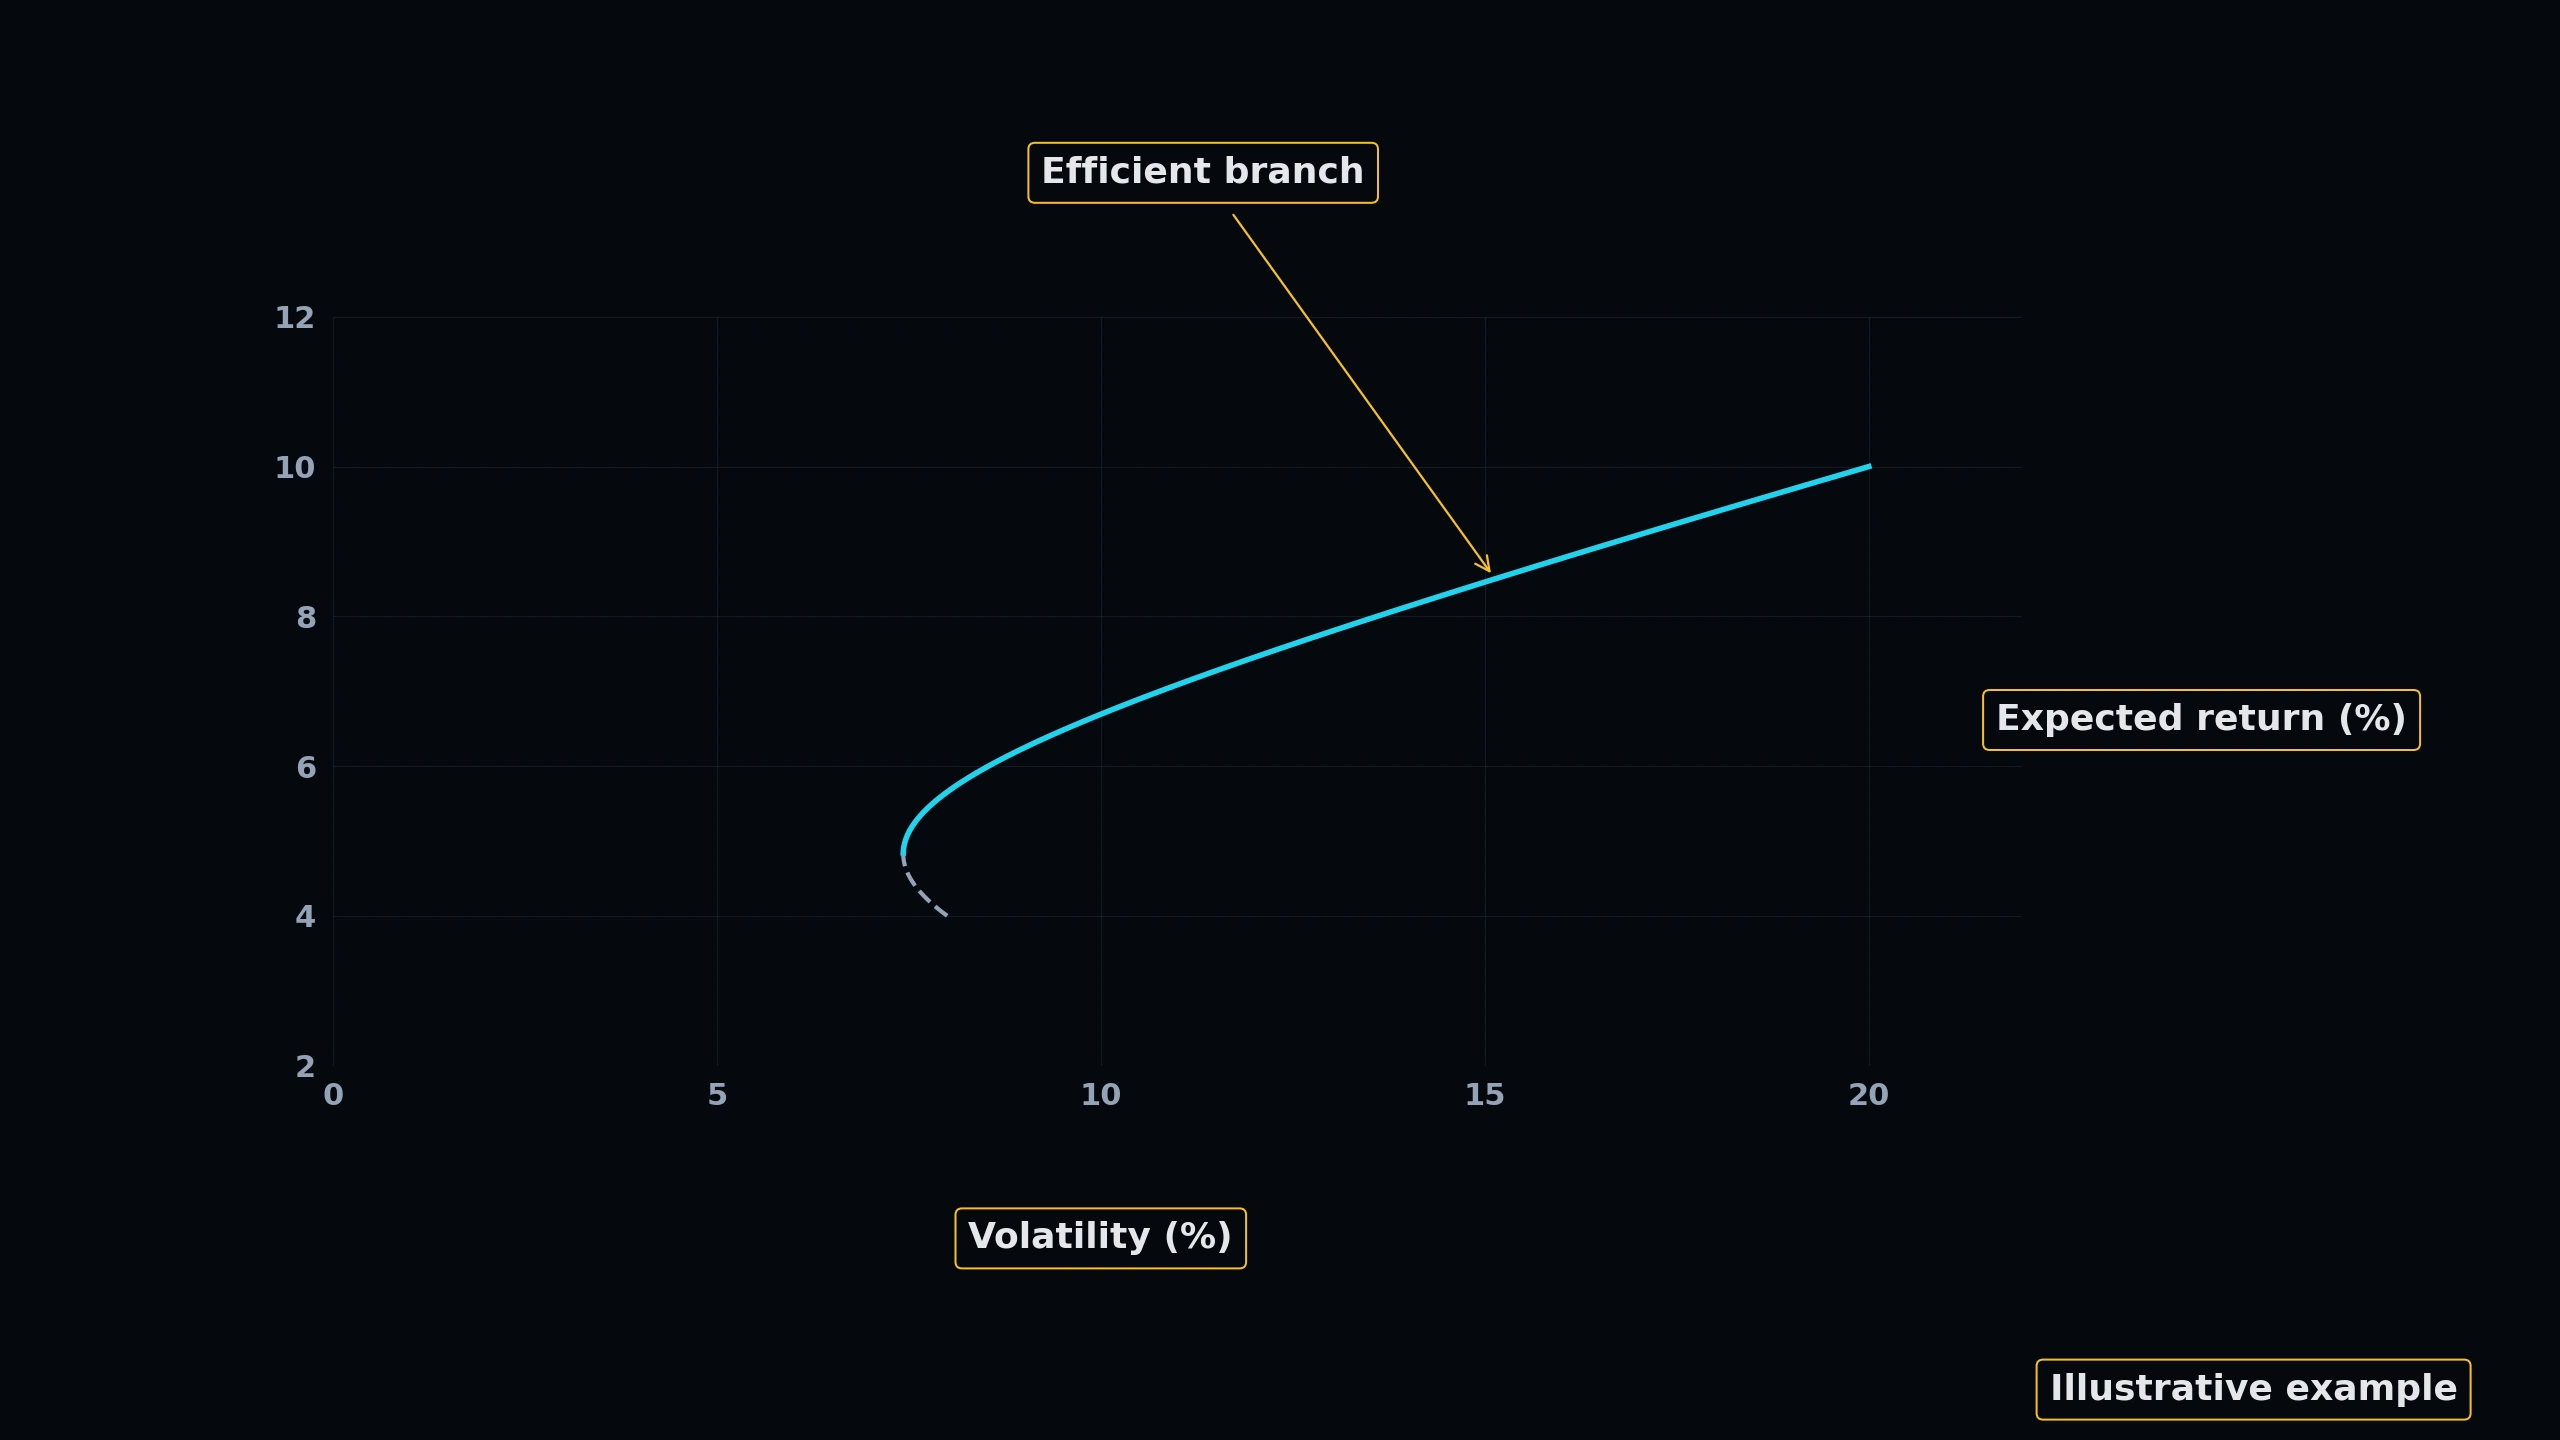
★ Efficient Frontier: The parabolic curve representing portfolios that offer the highest expected return for every possible level of portfolio variance.
2. Tangency Portfolio & Max Sharpe Ratio
The optimal risk-asset combination is the Tangency Portfolio, where the Capital Allocation Line (CAL) touches the efficient frontier.
This point maximizes the Sharpe Ratio: (E[R_p] - R_f) / σ_p, establishing the baseline benchmark for institutional multi-asset allocation.
 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
In Modern Portfolio Theory, what determines the total variance of a multi-asset portfolio beyond individual asset variances?
More lessons in this module
- 17.1: Capital Asset Pricing Model (CAPM), Beta, & Security Market Line
- 17.2: Multi-Factor Risk Models (Fama-French, Carhart, & Barra Factors)
- 17.3: Black-Litterman Model & Bayesian Asset Allocation
- 17.4: Risk Parity & Equal Risk Contribution (ERC) Portfolios
- 17.5: Dynamic Rebalancing, Tax-Loss Harvesting, & Friction Management
- 17.6: Alternative Beta, Risk Premia, & Smart Beta Indexing
- 17.7: Tail Risk Hedging & Downside Protection Frameworks
- 17.8: Institutional Asset-Liability Management (ALM) & Endowment Models
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.