
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
Lesson 8: 15.8: Building Sentiment-Driven Algorithmic Strategies & Risk Rules
Construct systematic sentiment trading models, stop-loss governance, sentiment regime filters, and backtesting.
1. Designing a Sentiment Strategy Architecture
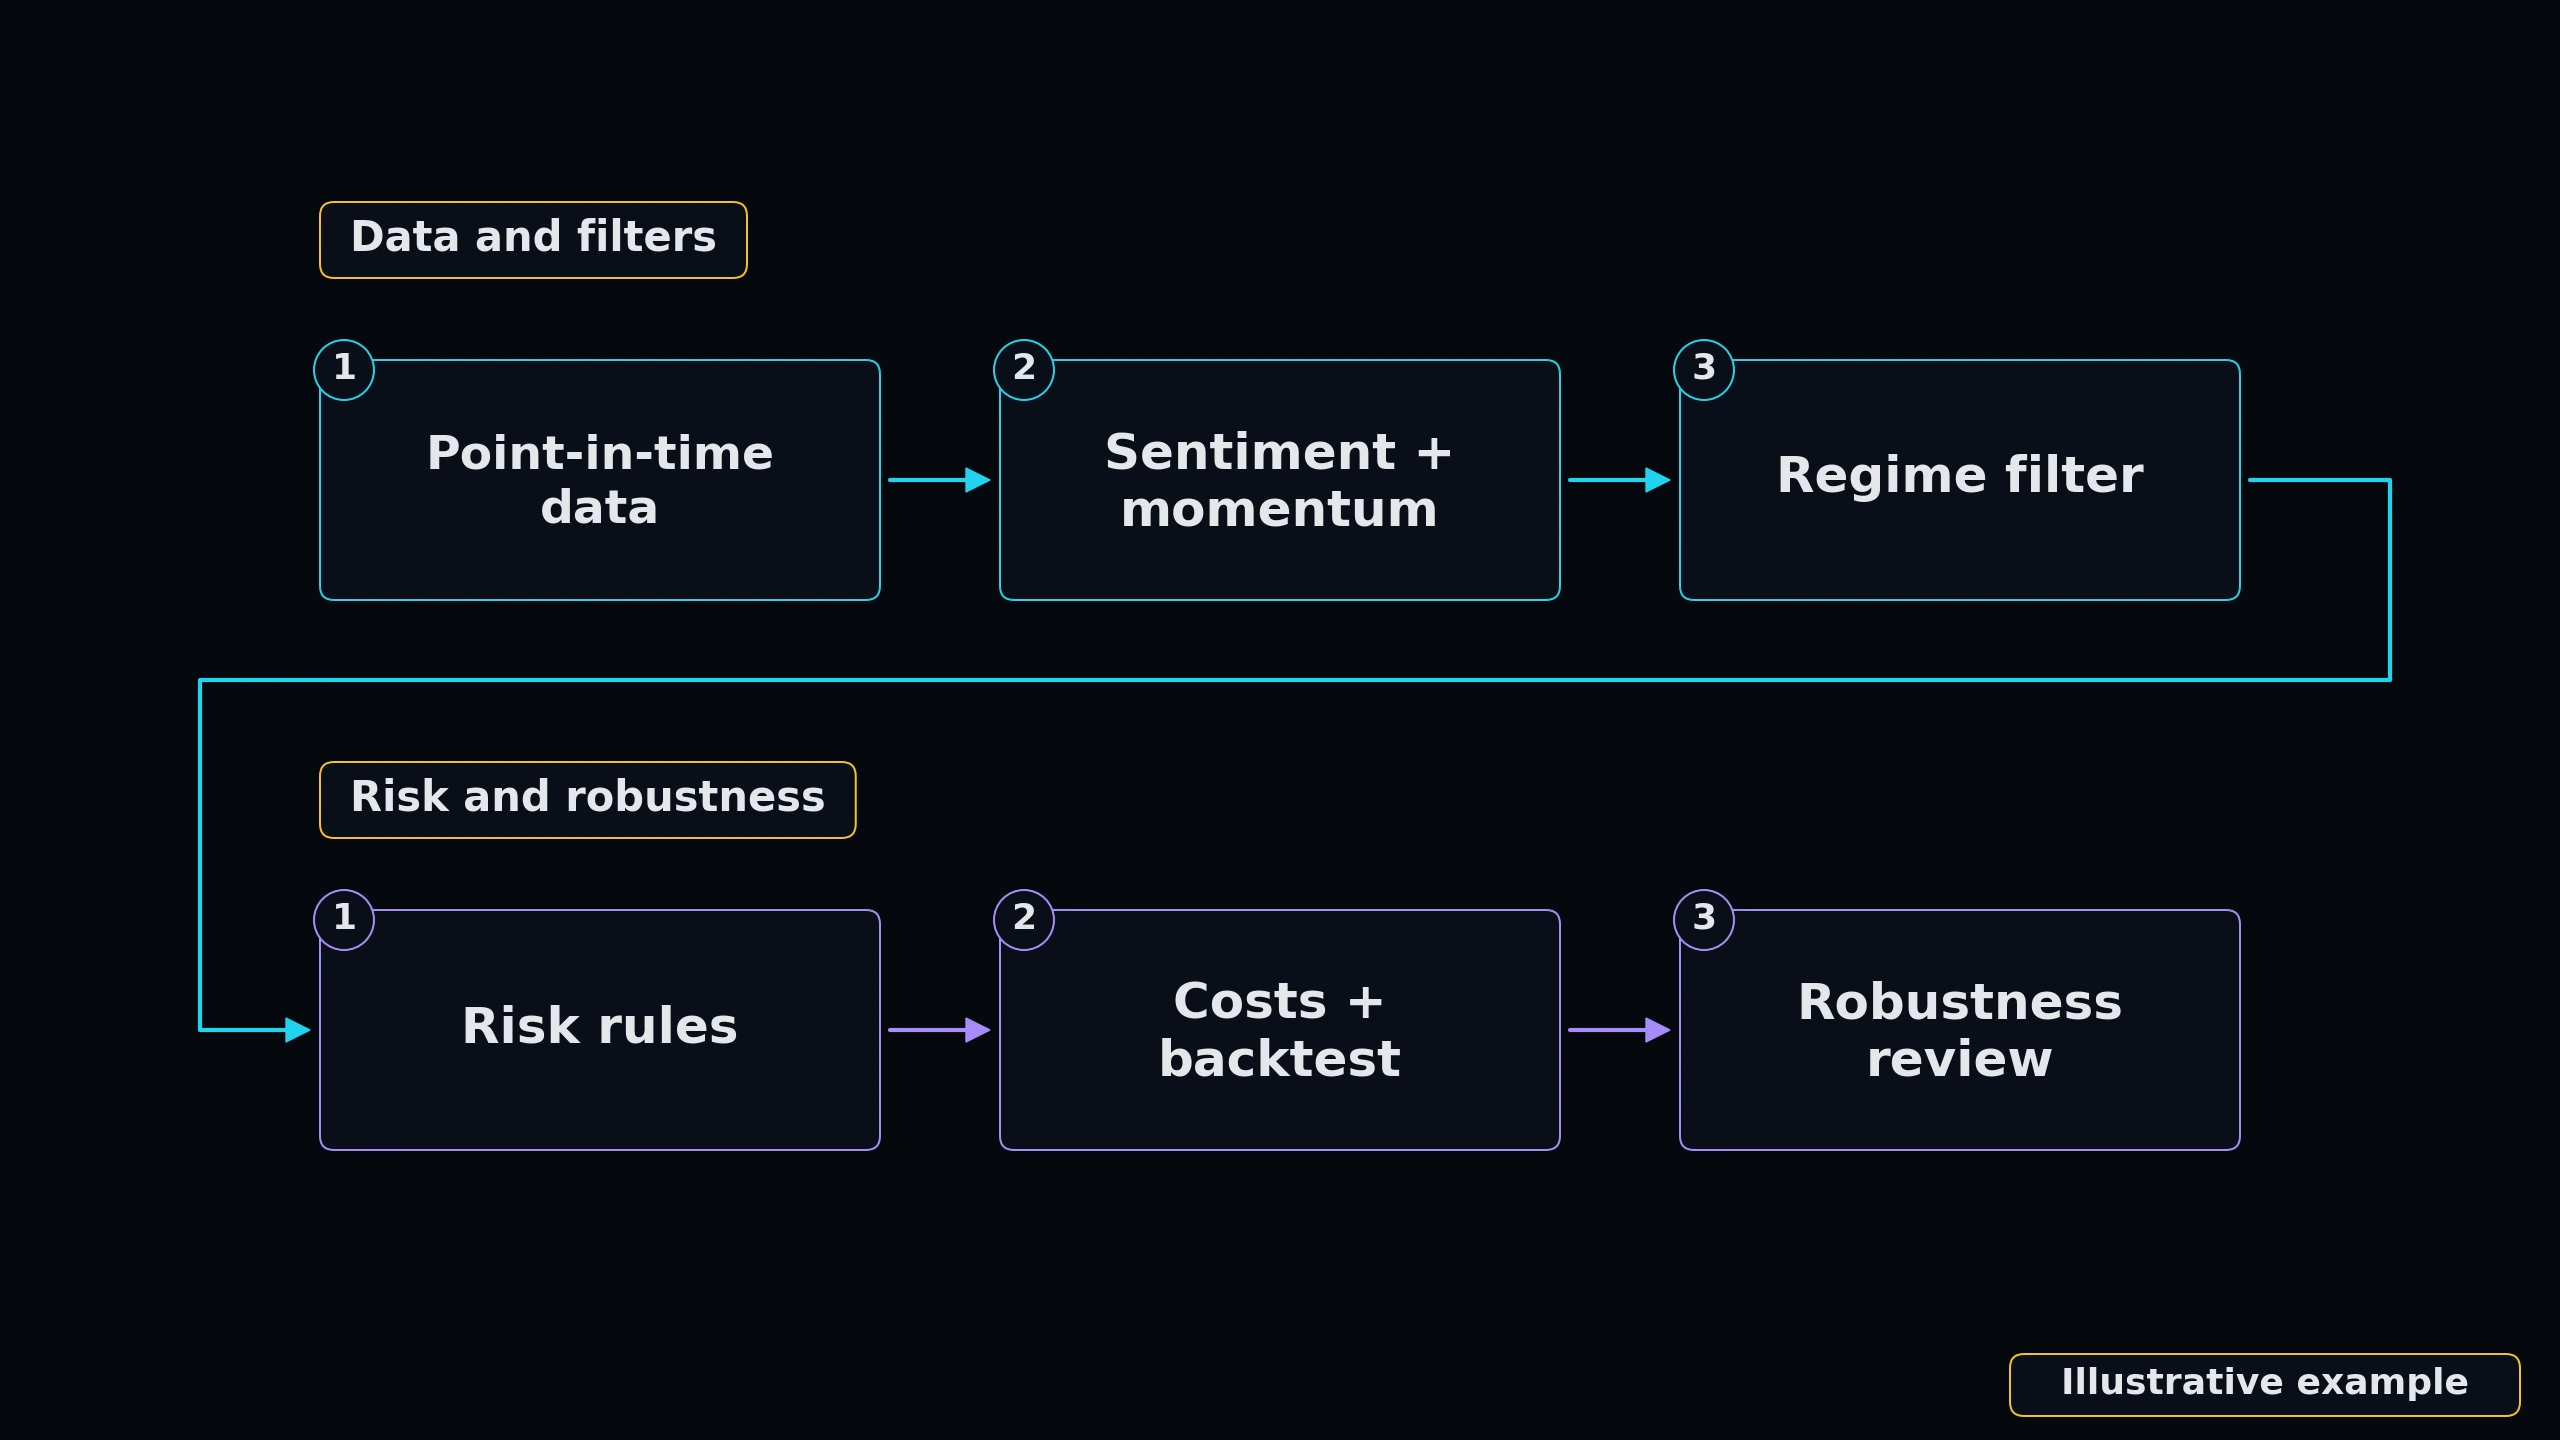
A production sentiment strategy combines alternative sentiment data with quantitative technical filters.
1. Entry Triggers: Go long when sentiment z-score exceeds +2.0 alongside positive price momentum; go short or exit when sentiment breaks below -1.5.
2. Regime Switching: Use macro VIX term structure to scale down position sizing during high-volatility panic regimes.
★ Dynamic Stop-Loss Governance: Incorporate volatility-adjusted ATR trailing stops to prevent premature shakeouts while protecting against sentiment reversal crashes.
2. Backtesting and Robustness Audits
Quant models must account for point-in-time alternative data availability, lookahead bias, and transaction costs to ensure realistic live performance.
 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
Why is point-in-time alternative data critical when backtesting sentiment-driven trading strategies?
More lessons in this module
- 15.0: Cognitive Biases in Trading
- 15.1: Prospect Theory & Mental Accounting in Portfolio Decisions
- 15.2: Sentiment Analysis Frameworks
- 15.3: Social Media & NLP Sentiment Signals
- 15.4: Market Psychology & Herd Behavior
- 15.5: Institutional Positioning Metrics
- 15.6: Quantitative Sentiment Modeling
- 15.7: Neurofinance & Decision Making Under Risk
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.