
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
Lesson 2: 15.2: Sentiment Analysis Frameworks
Deconstruct Put/Call ratios, VIX term structure backwardation/contango, and AAII survey sentiment.
1. Quantitative Sentiment Indicators
Market sentiment indicators measure the collective psychological positioning of retail and institutional participants.
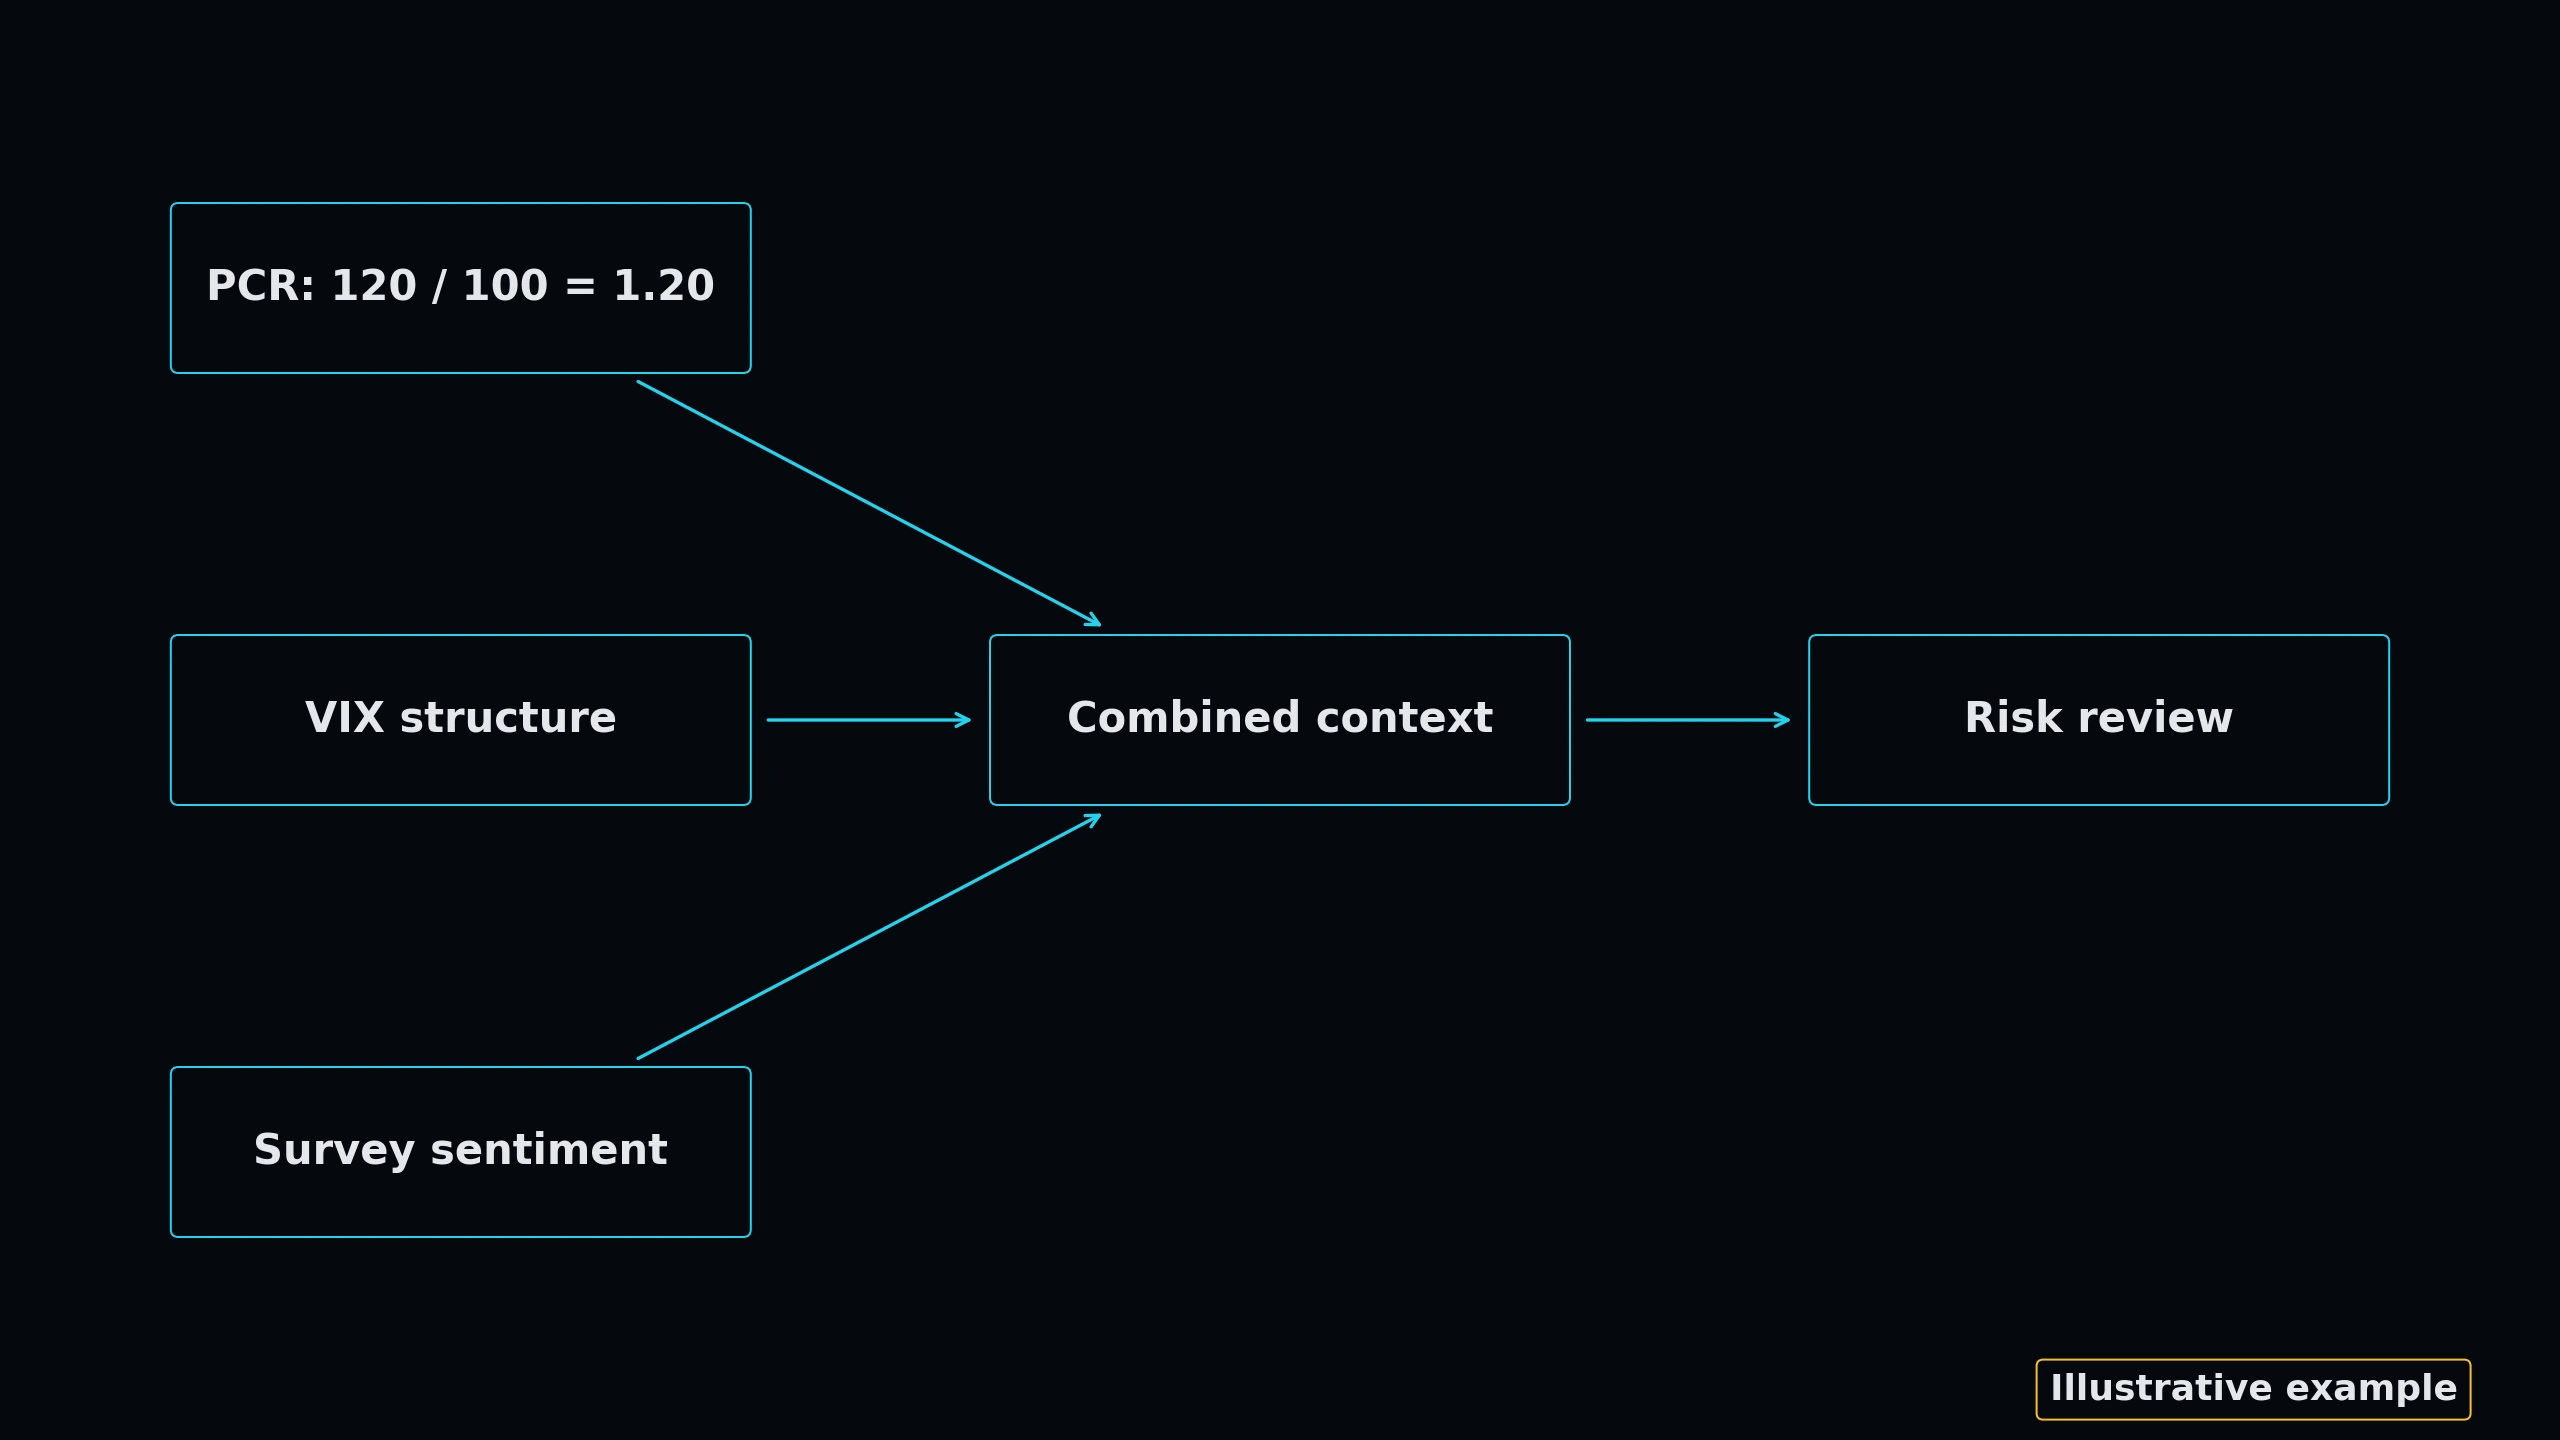
• Put/Call Volume Ratio (PCR): An unusually high PCR indicates extreme bearish hedging (often a contrarian bullish signal), while an extremely low PCR signals complacent bullishness.
★ VIX Futures Term Structure: When front-month VIX futures trade higher than back-month futures (backwardation), it signals acute, immediate market panic.
2. Survey & Breadth Metrics
Surveys like the AAII Sentiment Survey and CNN Fear & Greed Index aggregate subjective market participant expectations.
When combined with market breadth indicators (such as the percentage of stocks above their 200-day moving average), quants identify market extremes ripe for mean reversion.
 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
What does backwardation in the VIX futures term structure signify?
More lessons in this module
- 15.0: Cognitive Biases in Trading
- 15.1: Prospect Theory & Mental Accounting in Portfolio Decisions
- 15.3: Social Media & NLP Sentiment Signals
- 15.4: Market Psychology & Herd Behavior
- 15.5: Institutional Positioning Metrics
- 15.6: Quantitative Sentiment Modeling
- 15.7: Neurofinance & Decision Making Under Risk
- 15.8: Building Sentiment-Driven Algorithmic Strategies & Risk Rules
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.