
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
Lesson 4: 15.4: Market Psychology & Herd Behavior
Study market euphoria, panic cascades, short squeeze dynamics, and feedback loop mechanisms.
1. The Anatomy of Speculative Bubbles and Panics
Market prices are driven by reflexive feedback loops where rising prices attract momentum buyers, generating euphoria that decouples valuation from fundamental cash flows.
Herding behavior occurs when investors abandon independent analysis and follow group consensus due to fear of missing out (FOMO) or social validation.
★ Short Squeeze Dynamics: When a heavily shorted stock rises unexpectedly, short sellers are forced to buy shares to cover positions, creating a self-reinforcing vertical price spike.
2. Liquidity Cascades and Forced Liquidations
During market panics, stop-loss triggers and margin calls force automated selling across funds.
This forced liquidation consumes available order book liquidity, causing sharp price gaps down unrelated to long-term asset fundamentals.
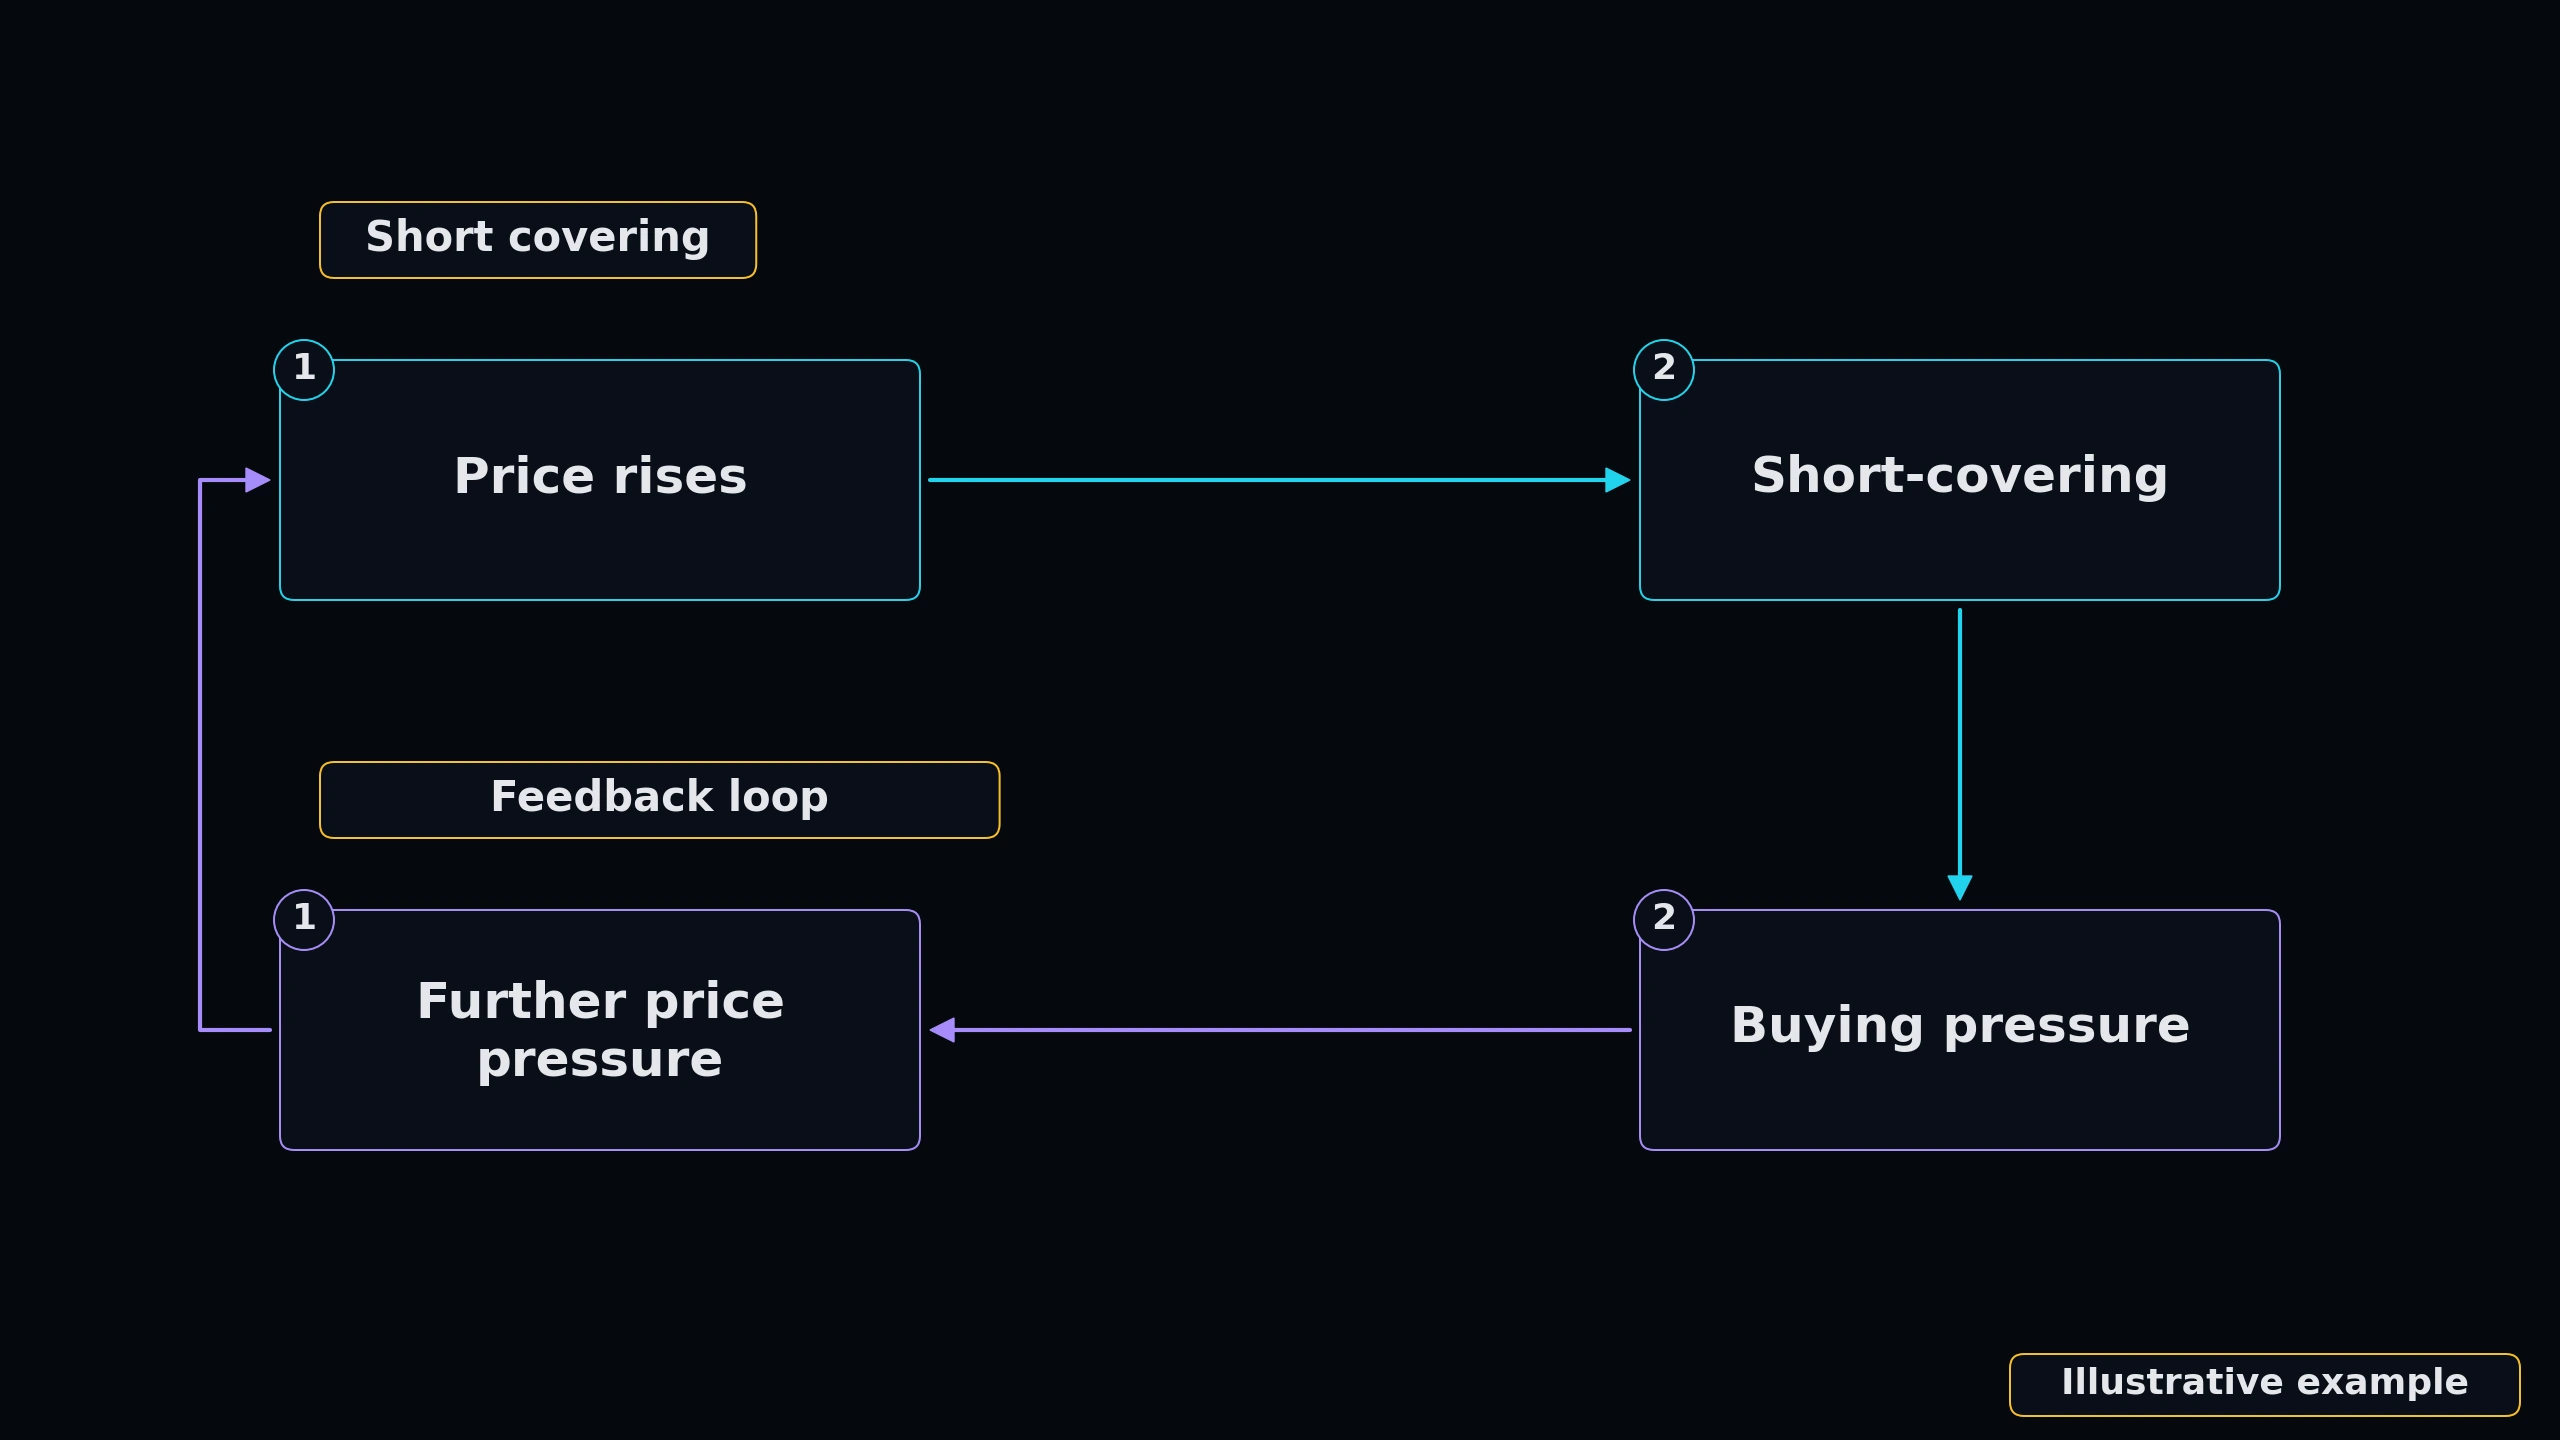 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
What causes a short squeeze to accelerate violently upward?
More lessons in this module
- 15.0: Cognitive Biases in Trading
- 15.1: Prospect Theory & Mental Accounting in Portfolio Decisions
- 15.2: Sentiment Analysis Frameworks
- 15.3: Social Media & NLP Sentiment Signals
- 15.5: Institutional Positioning Metrics
- 15.6: Quantitative Sentiment Modeling
- 15.7: Neurofinance & Decision Making Under Risk
- 15.8: Building Sentiment-Driven Algorithmic Strategies & Risk Rules
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.