
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
Lesson 5: 15.5: Institutional Positioning Metrics
Analyze CFTC Commitment of Traders (COT) reports, Dark Pool Index (DIX), and Gamma Exposure (GEX).
1. Deconstructing Institutional Positioning
Retail sentiment represents crowd psychology, but institutional positioning reflects real capital allocation.
• CFTC COT Report: Weekly breakdown of futures market positioning across Commercial Hedgers, Non-Commercial Speculators, and Small Traders. Extreme commercial net-long positioning often marks macro market bottoms.
★ Dark Pool Index (DIX): Tracks the proportion of dark pool dollar volume executed as buy-side absorption versus sell-side distribution.
2. Gamma Exposure (GEX) Positioning
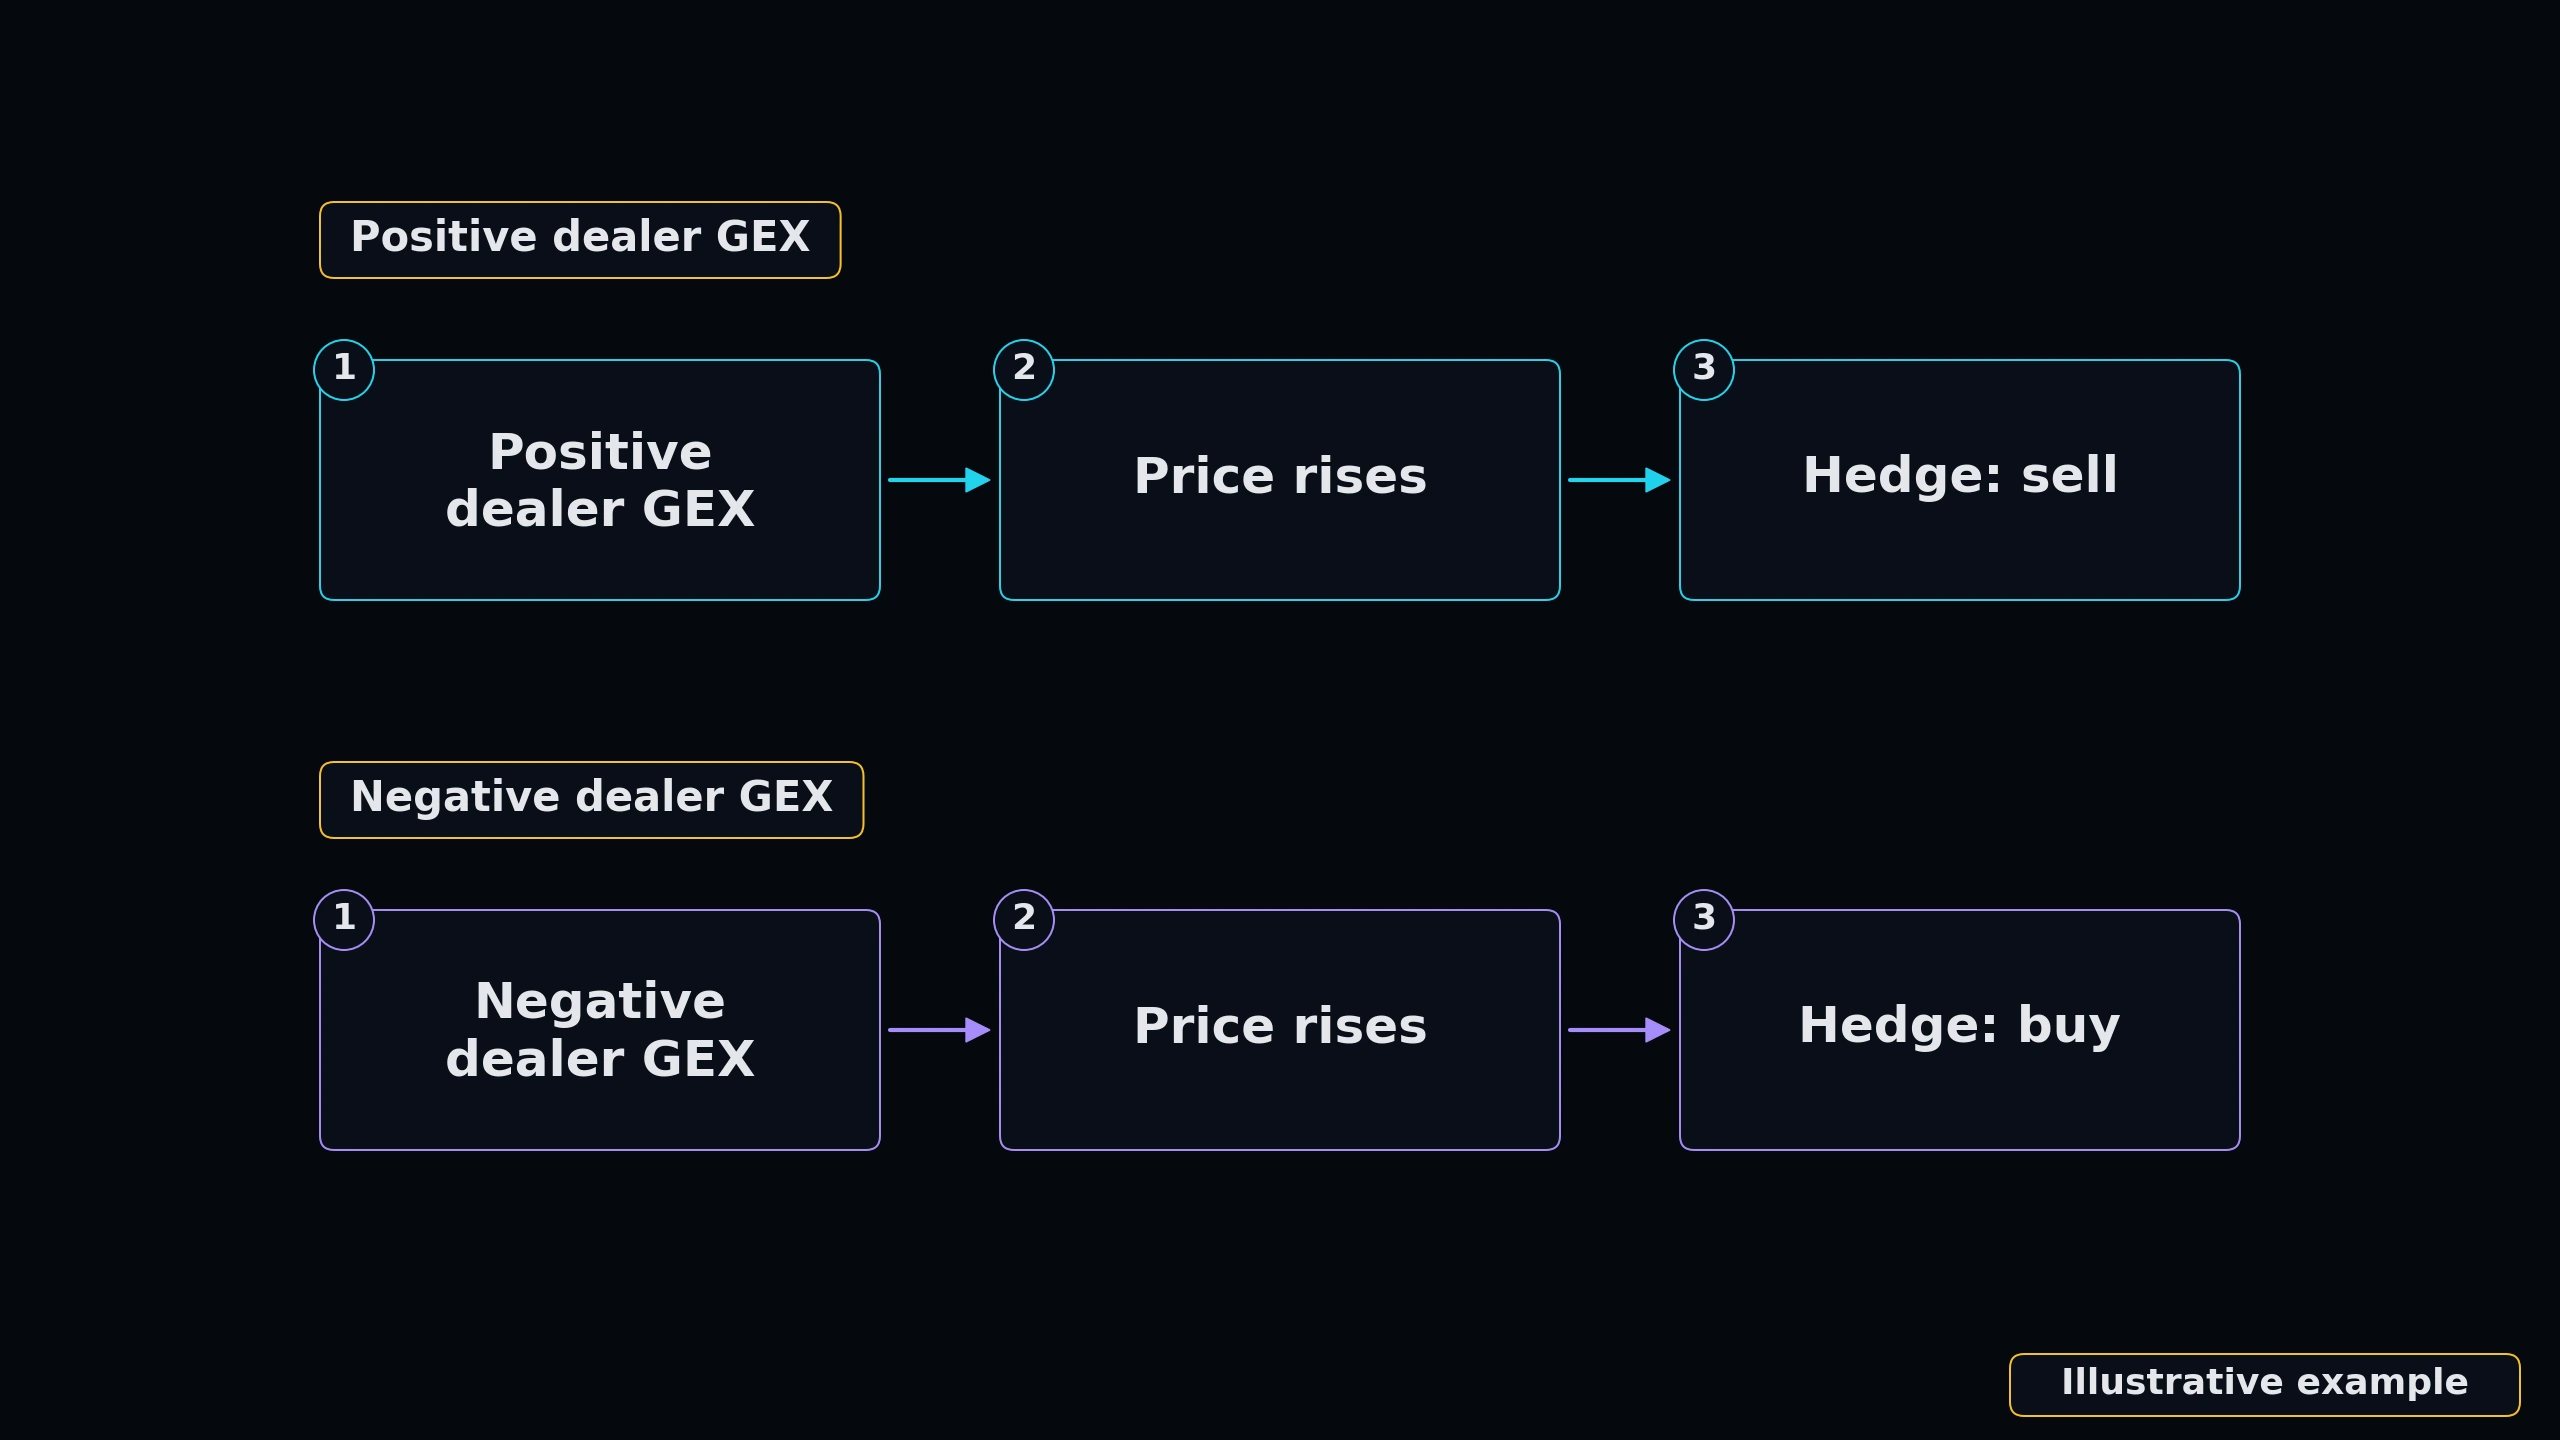
Calculating dealer option gamma (GEX) reveals whether market makers must trade in the direction of market moves (negative GEX) or against them (positive GEX).
In positive GEX environments, dealer hedging dampens volatility, keeping prices range-bound.
 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
In CFTC Commitment of Traders (COT) reports, which group's positioning is considered the smart money benchmark for macro bottoms?
More lessons in this module
- 15.0: Cognitive Biases in Trading
- 15.1: Prospect Theory & Mental Accounting in Portfolio Decisions
- 15.2: Sentiment Analysis Frameworks
- 15.3: Social Media & NLP Sentiment Signals
- 15.4: Market Psychology & Herd Behavior
- 15.6: Quantitative Sentiment Modeling
- 15.7: Neurofinance & Decision Making Under Risk
- 15.8: Building Sentiment-Driven Algorithmic Strategies & Risk Rules
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.