
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
Lesson 2: 13.2: Credit Default Swaps (CDS) & Default Protection
Analyze single-name and index CDS contracts, protection buyers/sellers, and credit event triggers.
1. How Credit Default Swaps Work
A Credit Default Swap (CDS) functions as financial insurance against the default or restructuring of a reference entity (a corporate bond issuer or sovereign nation).
The protection buyer pays a quarterly premium (spread) to the protection seller. In return, if a defined 'Credit Event' occurs (such as bankruptcy, failure to pay, or debt restructuring), the protection seller must compensate the buyer for the credit loss.
★ Credit Spreads: Widening CDS spreads indicate that market participants perceive a higher probability of default for the reference entity.
2. Single-Name CDS vs. Index CDS
• Single-Name CDS: Protects against the credit default of one specific corporation or sovereign entity.
• Index CDS (e.g., CDX, iTraxx): Standardized baskets of multiple credit entities that allow institutions to trade broad corporate credit risk, portfolio default risk, and systemic macroeconomic health.
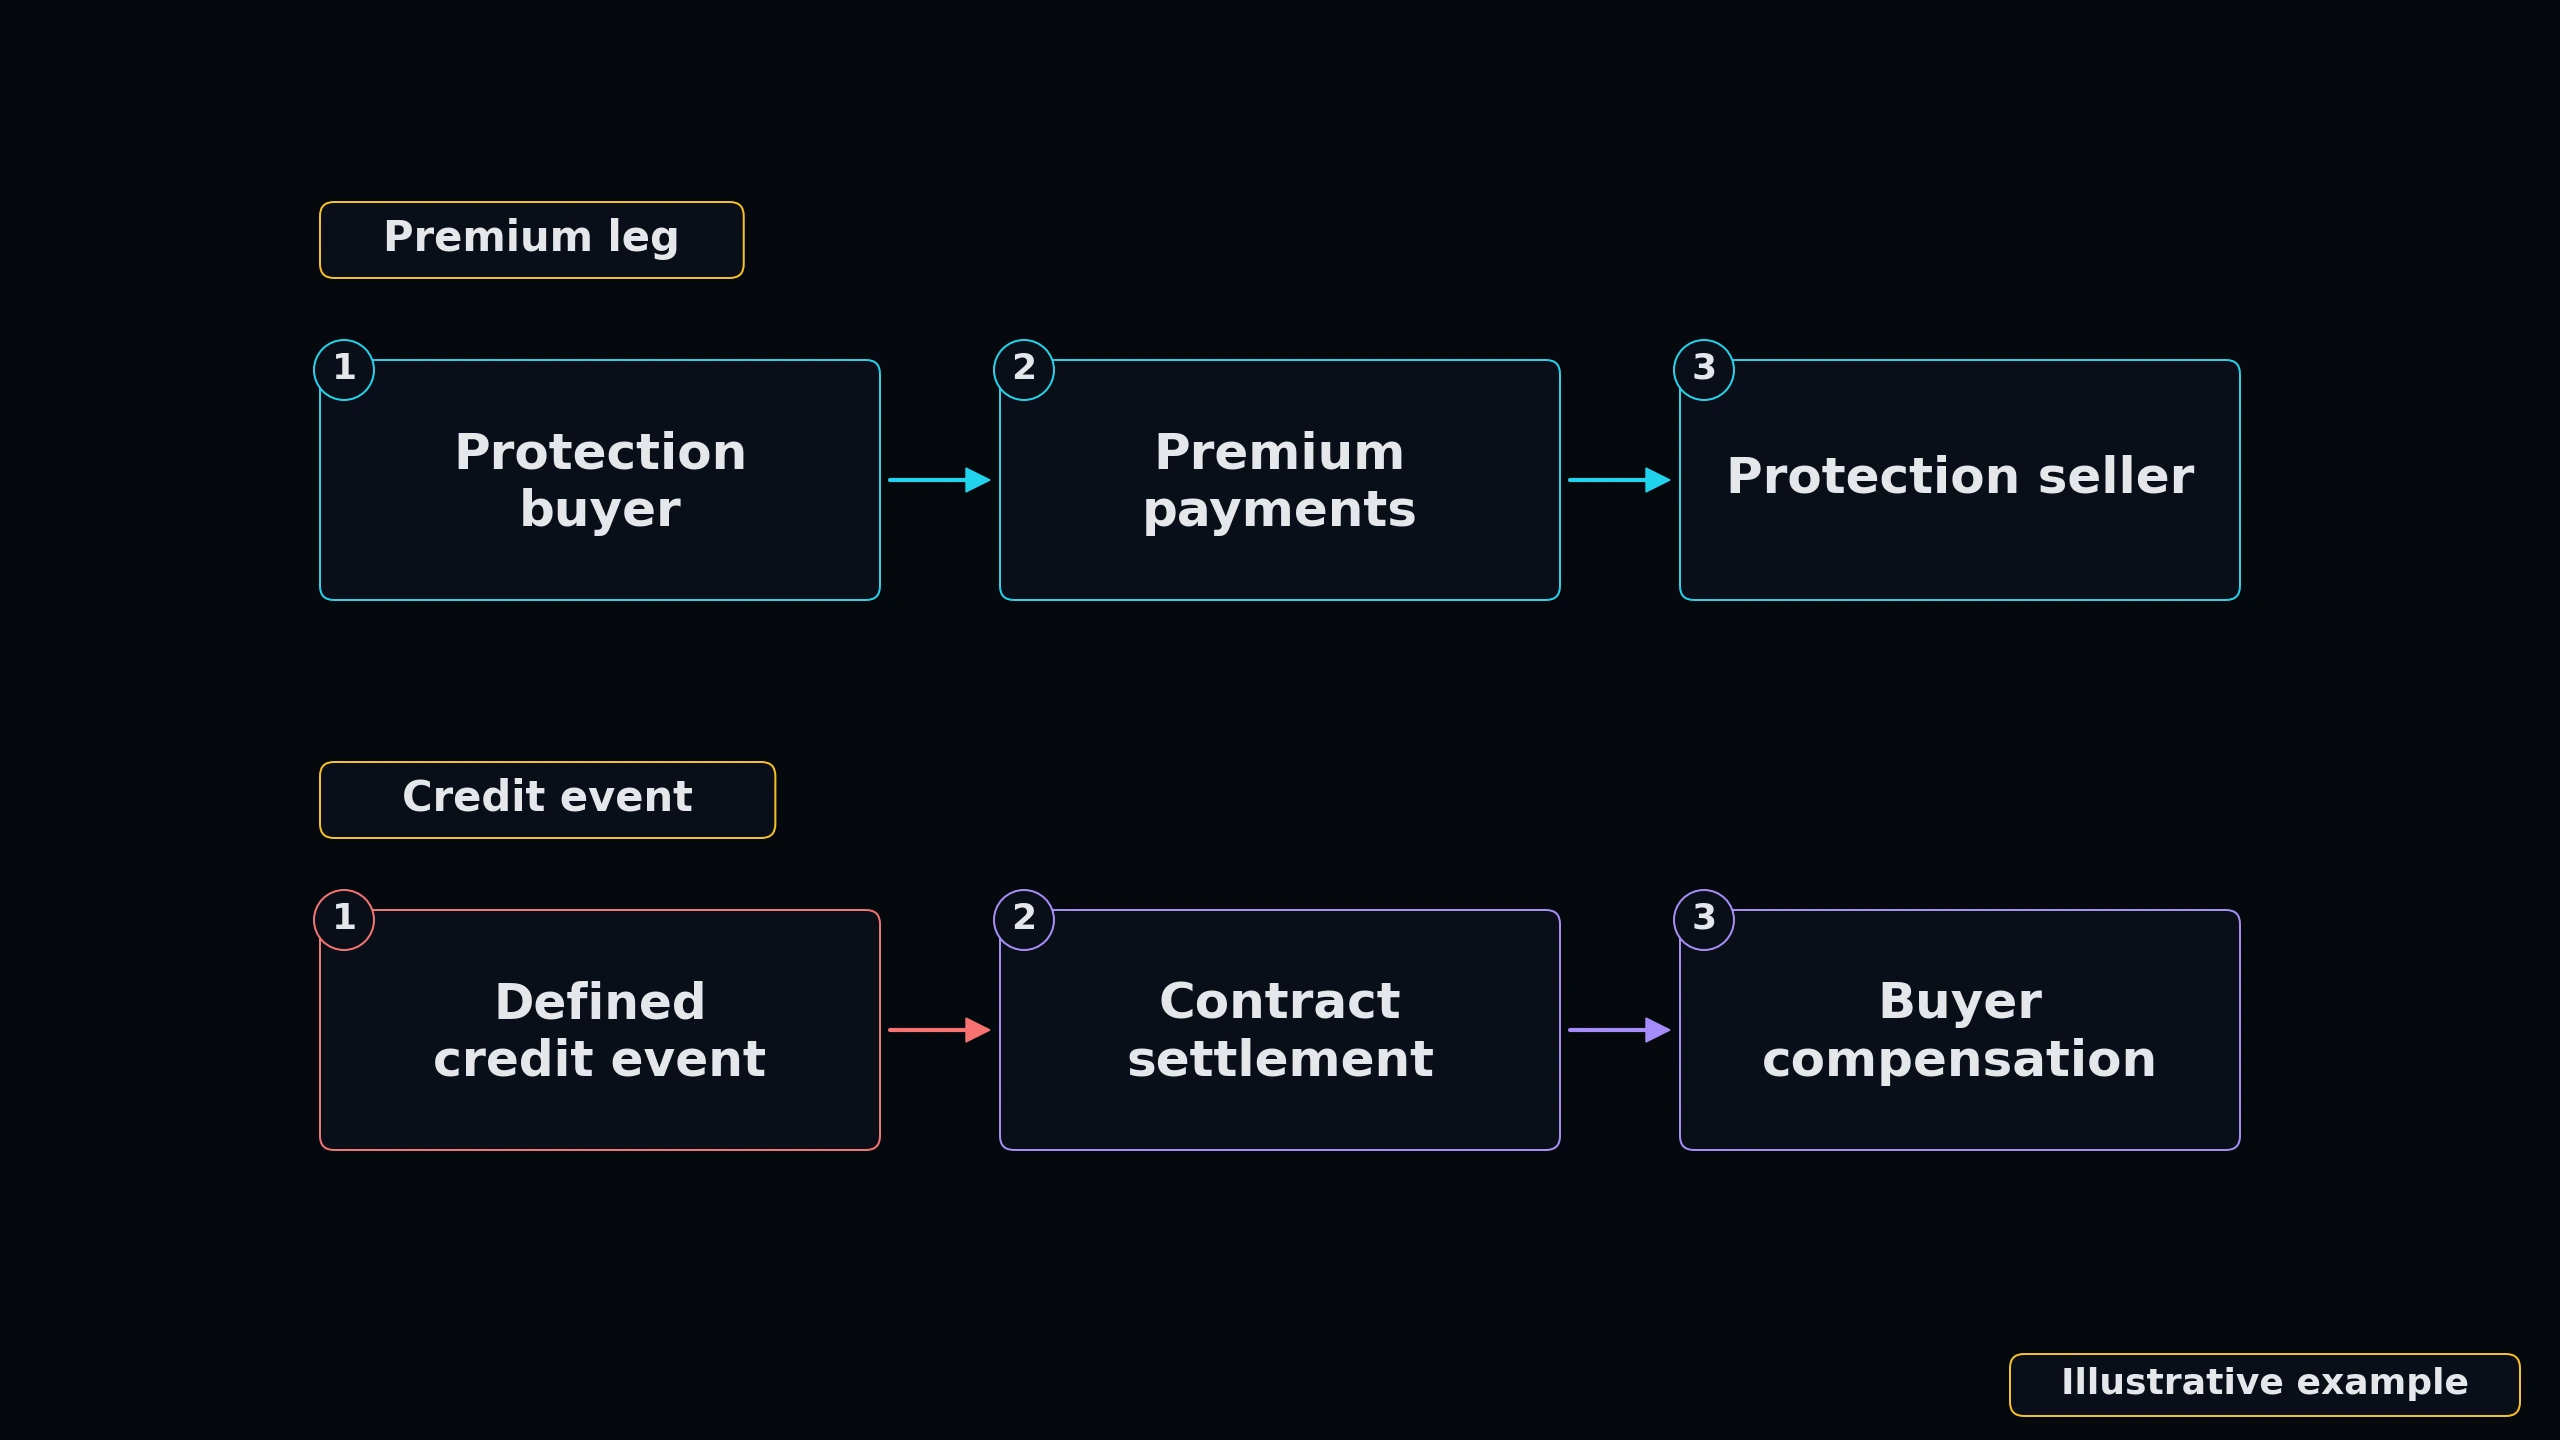 Click to enlarge
Options Structure Exploration
Options are contracts cleared in the bid-ask auction market. Interact with the Order Book below to understand how buy offers (bids) and sell offers (asks) intersect, and inspect the structural breakdown between Call and Put contracts.
Limit Order Book & Spread Interface
Hover over ASK or BID to dissect the auction market dynamics.
Right to Buy
- Outlook: Bullish (Goes up)
- Risk: Capped to premium paid
- Profit: Scales as stock surges
Right to Sell
- Outlook: Bearish (Goes down)
- Risk: Capped to premium paid
- Profit: Scales as stock falls
KNOWLEDGE RECONNAISSANCE
If a company's financial distress grows severe, what happens to the pricing of its Credit Default Swap (CDS) protection?
More lessons in this module
- 13.0: Introduction to Swaps & Derivatives Architecture
- 13.1: Interest Rate Swaps (IRS) Mechanics
- 13.3: Total Return Swaps (TRS) & Synthetic Exposure
- 13.4: Foreign Exchange Swaps & Cross-Currency Swaps
- 13.5: Exotic Options: Barrier, Digital & Lookback Options
- 13.6: Structured Notes & Capital Protection Products
- 13.7: Counterparty Risk, ISDA Agreements & Collateral (CSA)
- 13.8: Practical Derivatives Application: Corporate Risk Playbook
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.