
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Lesson 0: 13.0: Introduction to Swaps & Derivatives Architecture
Understand off-exchange derivative contracts, notional principal, cash flow exchanges, and ISDA frameworks.
1. The Over-the-Counter (OTC) Derivatives Ecosystem
Financial derivatives are contracts whose value is derived from an underlying asset, benchmark, or index. While exchange-traded derivatives (like standard options and futures) feature standardized terms and central order books, the vast majority of global derivative volume exists in the Over-the-Counter (OTC) market.
In the OTC market, institutional counterparties negotiate bespoke bilateral agreements tailored to specific maturities, cash flow schedules, and hedging requirements.
★ Notional Principal: In swap contracts, the notional principal is the reference amount used to calculate interest and cash flow payments. Unlike loan contracts, the principal itself is rarely exchanged between counterparties.
2. Cash Flow Exchanges and Valuation
A swap is a contractual agreement between two parties to exchange sequences of cash flows over a specified timeframe.
These cash flows are calculated based on benchmark interest rates, foreign exchange rates, commodity prices, or credit default events. Swaps are marked-to-market continuously, creating daily variation margin requirements to protect against counterparty default.
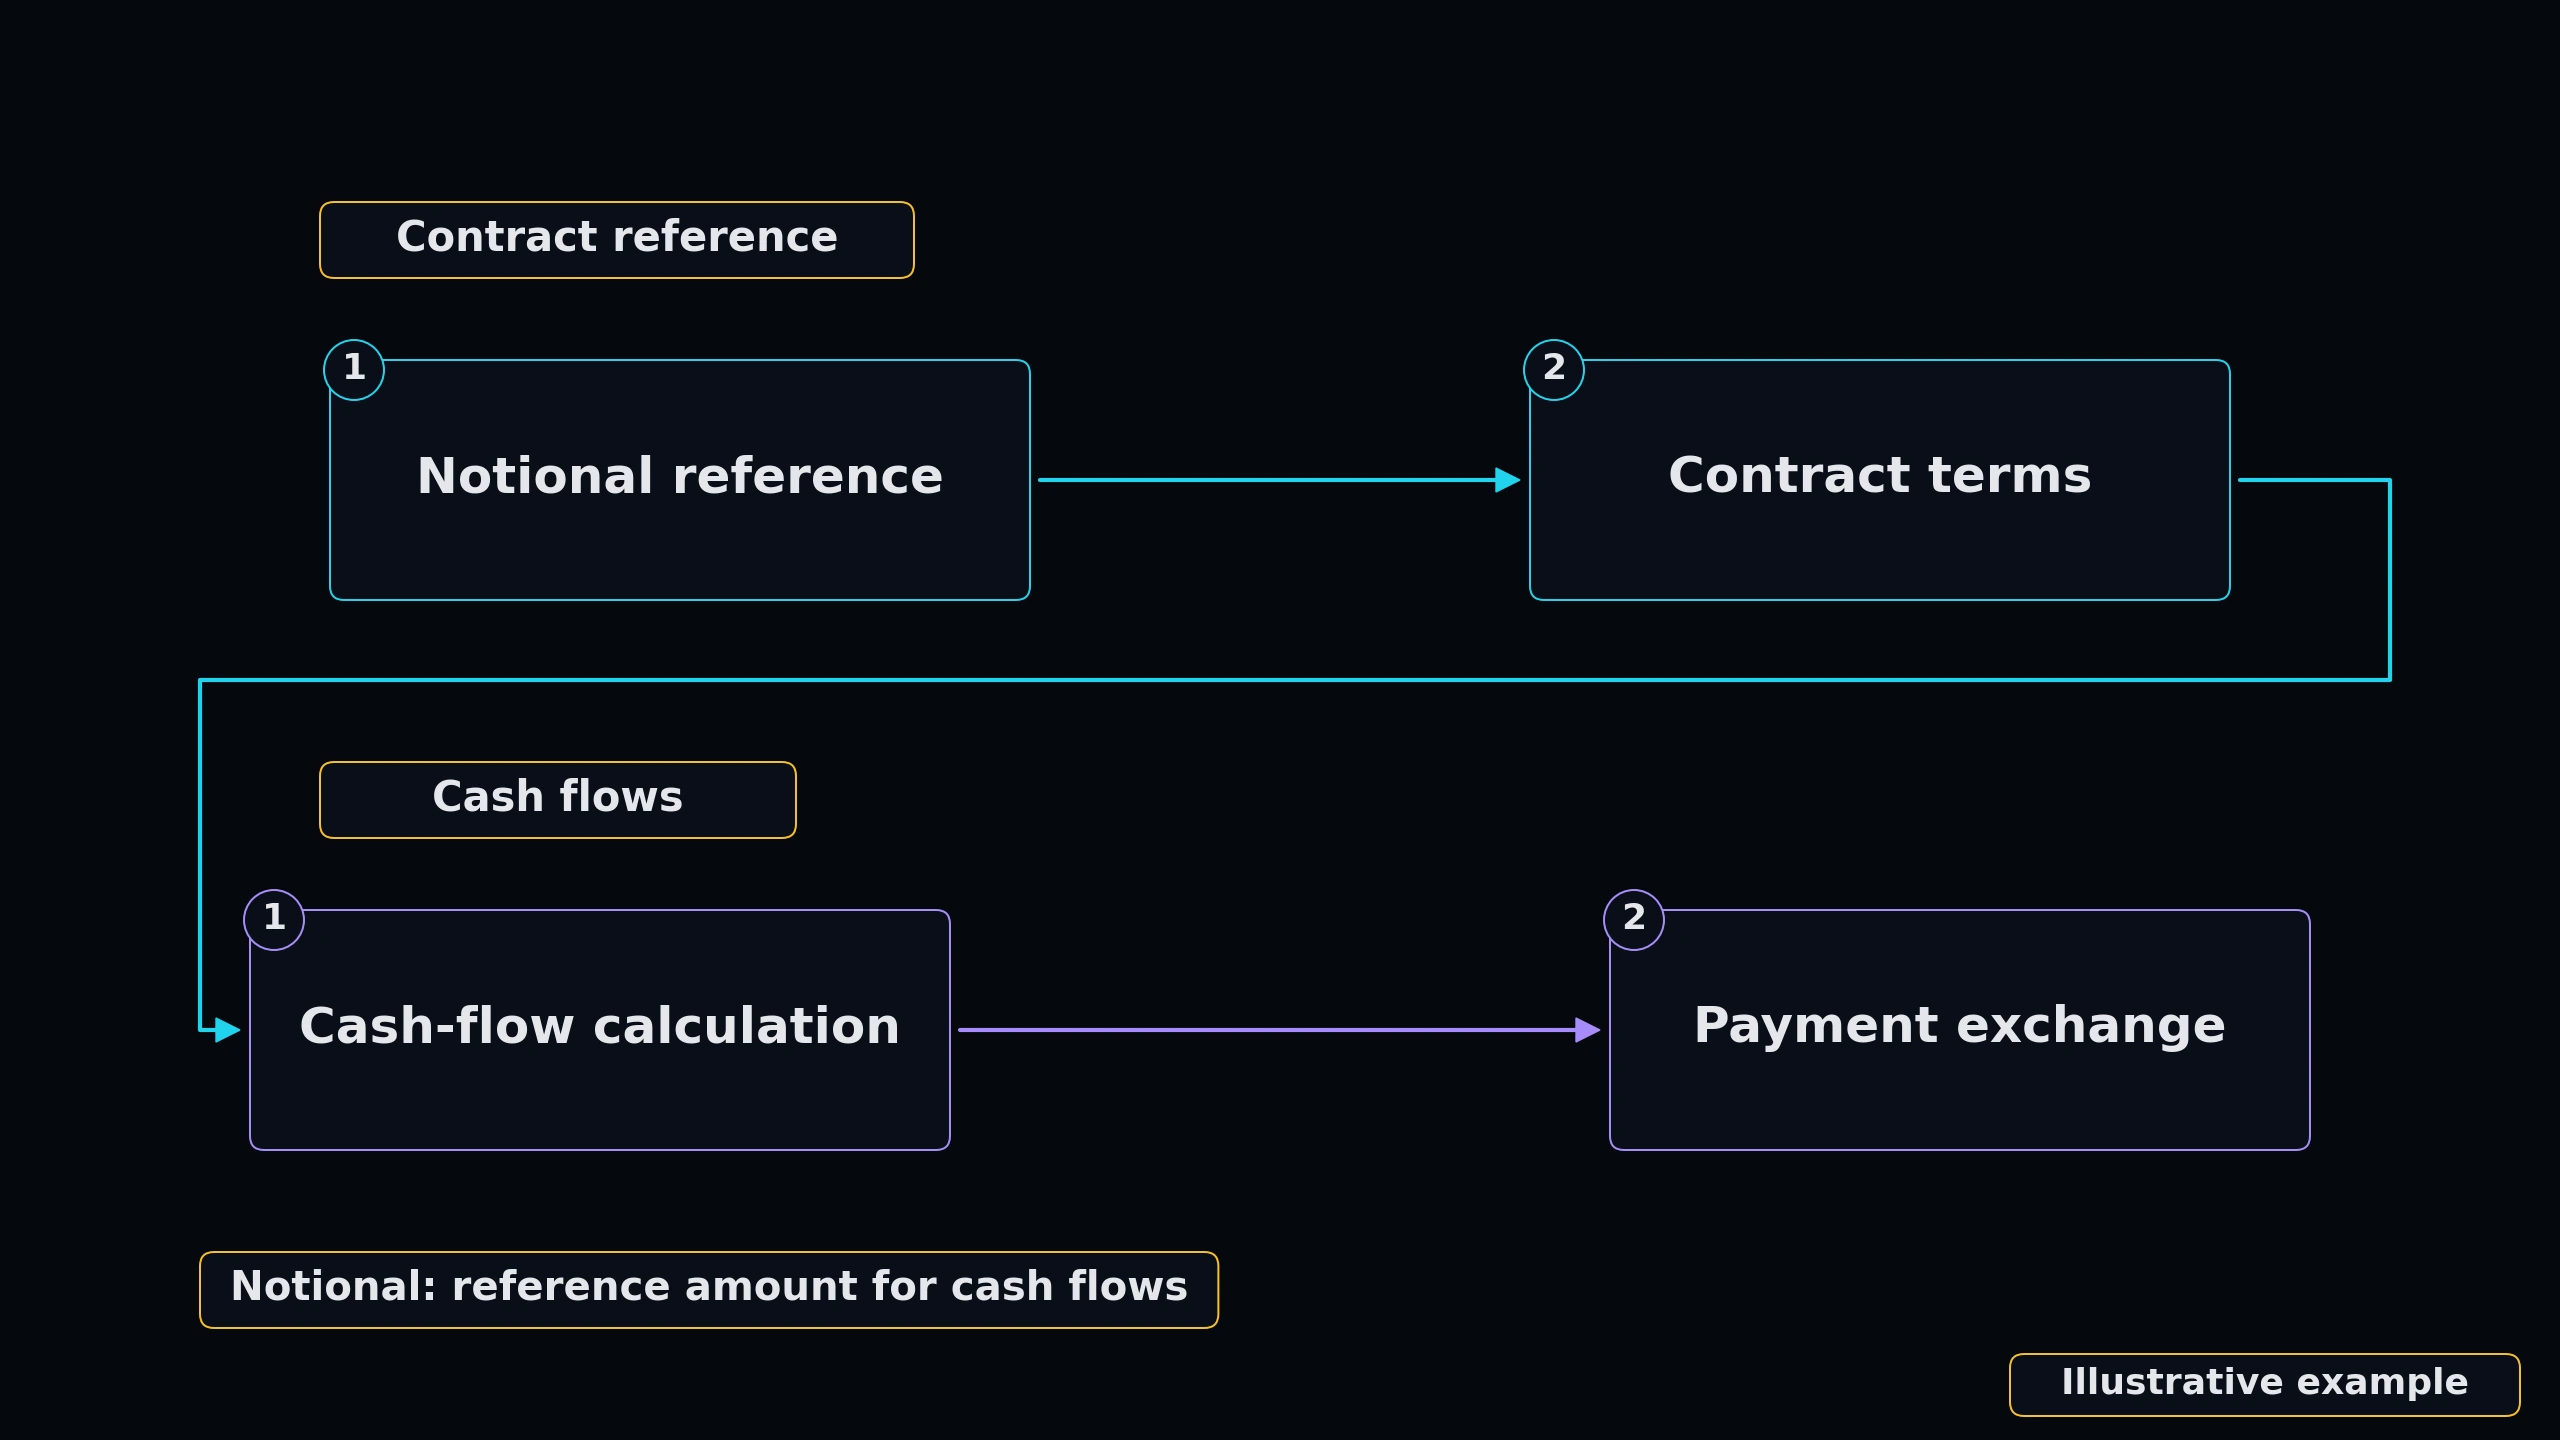 Click to enlarge
Options Structure Exploration
Options are contracts cleared in the bid-ask auction market. Interact with the Order Book below to understand how buy offers (bids) and sell offers (asks) intersect, and inspect the structural breakdown between Call and Put contracts.
Limit Order Book & Spread Interface
Hover over ASK or BID to dissect the auction market dynamics.
Right to Buy
- Outlook: Bullish (Goes up)
- Risk: Capped to premium paid
- Profit: Scales as stock surges
Right to Sell
- Outlook: Bearish (Goes down)
- Risk: Capped to premium paid
- Profit: Scales as stock falls
KNOWLEDGE RECONNAISSANCE
What is the primary function of the 'notional principal' in an interest rate swap contract?
More lessons in this module
- 13.1: Interest Rate Swaps (IRS) Mechanics
- 13.2: Credit Default Swaps (CDS) & Default Protection
- 13.3: Total Return Swaps (TRS) & Synthetic Exposure
- 13.4: Foreign Exchange Swaps & Cross-Currency Swaps
- 13.5: Exotic Options: Barrier, Digital & Lookback Options
- 13.6: Structured Notes & Capital Protection Products
- 13.7: Counterparty Risk, ISDA Agreements & Collateral (CSA)
- 13.8: Practical Derivatives Application: Corporate Risk Playbook
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.