
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Lesson 4: 8.3: Volume Weighted Average Price (VWAP) & Anchored VWAP
Integrate price, volume, and time to identify true institutional fair value and establish execution benchmarks.
1. VWAP as the Institutional Benchmark
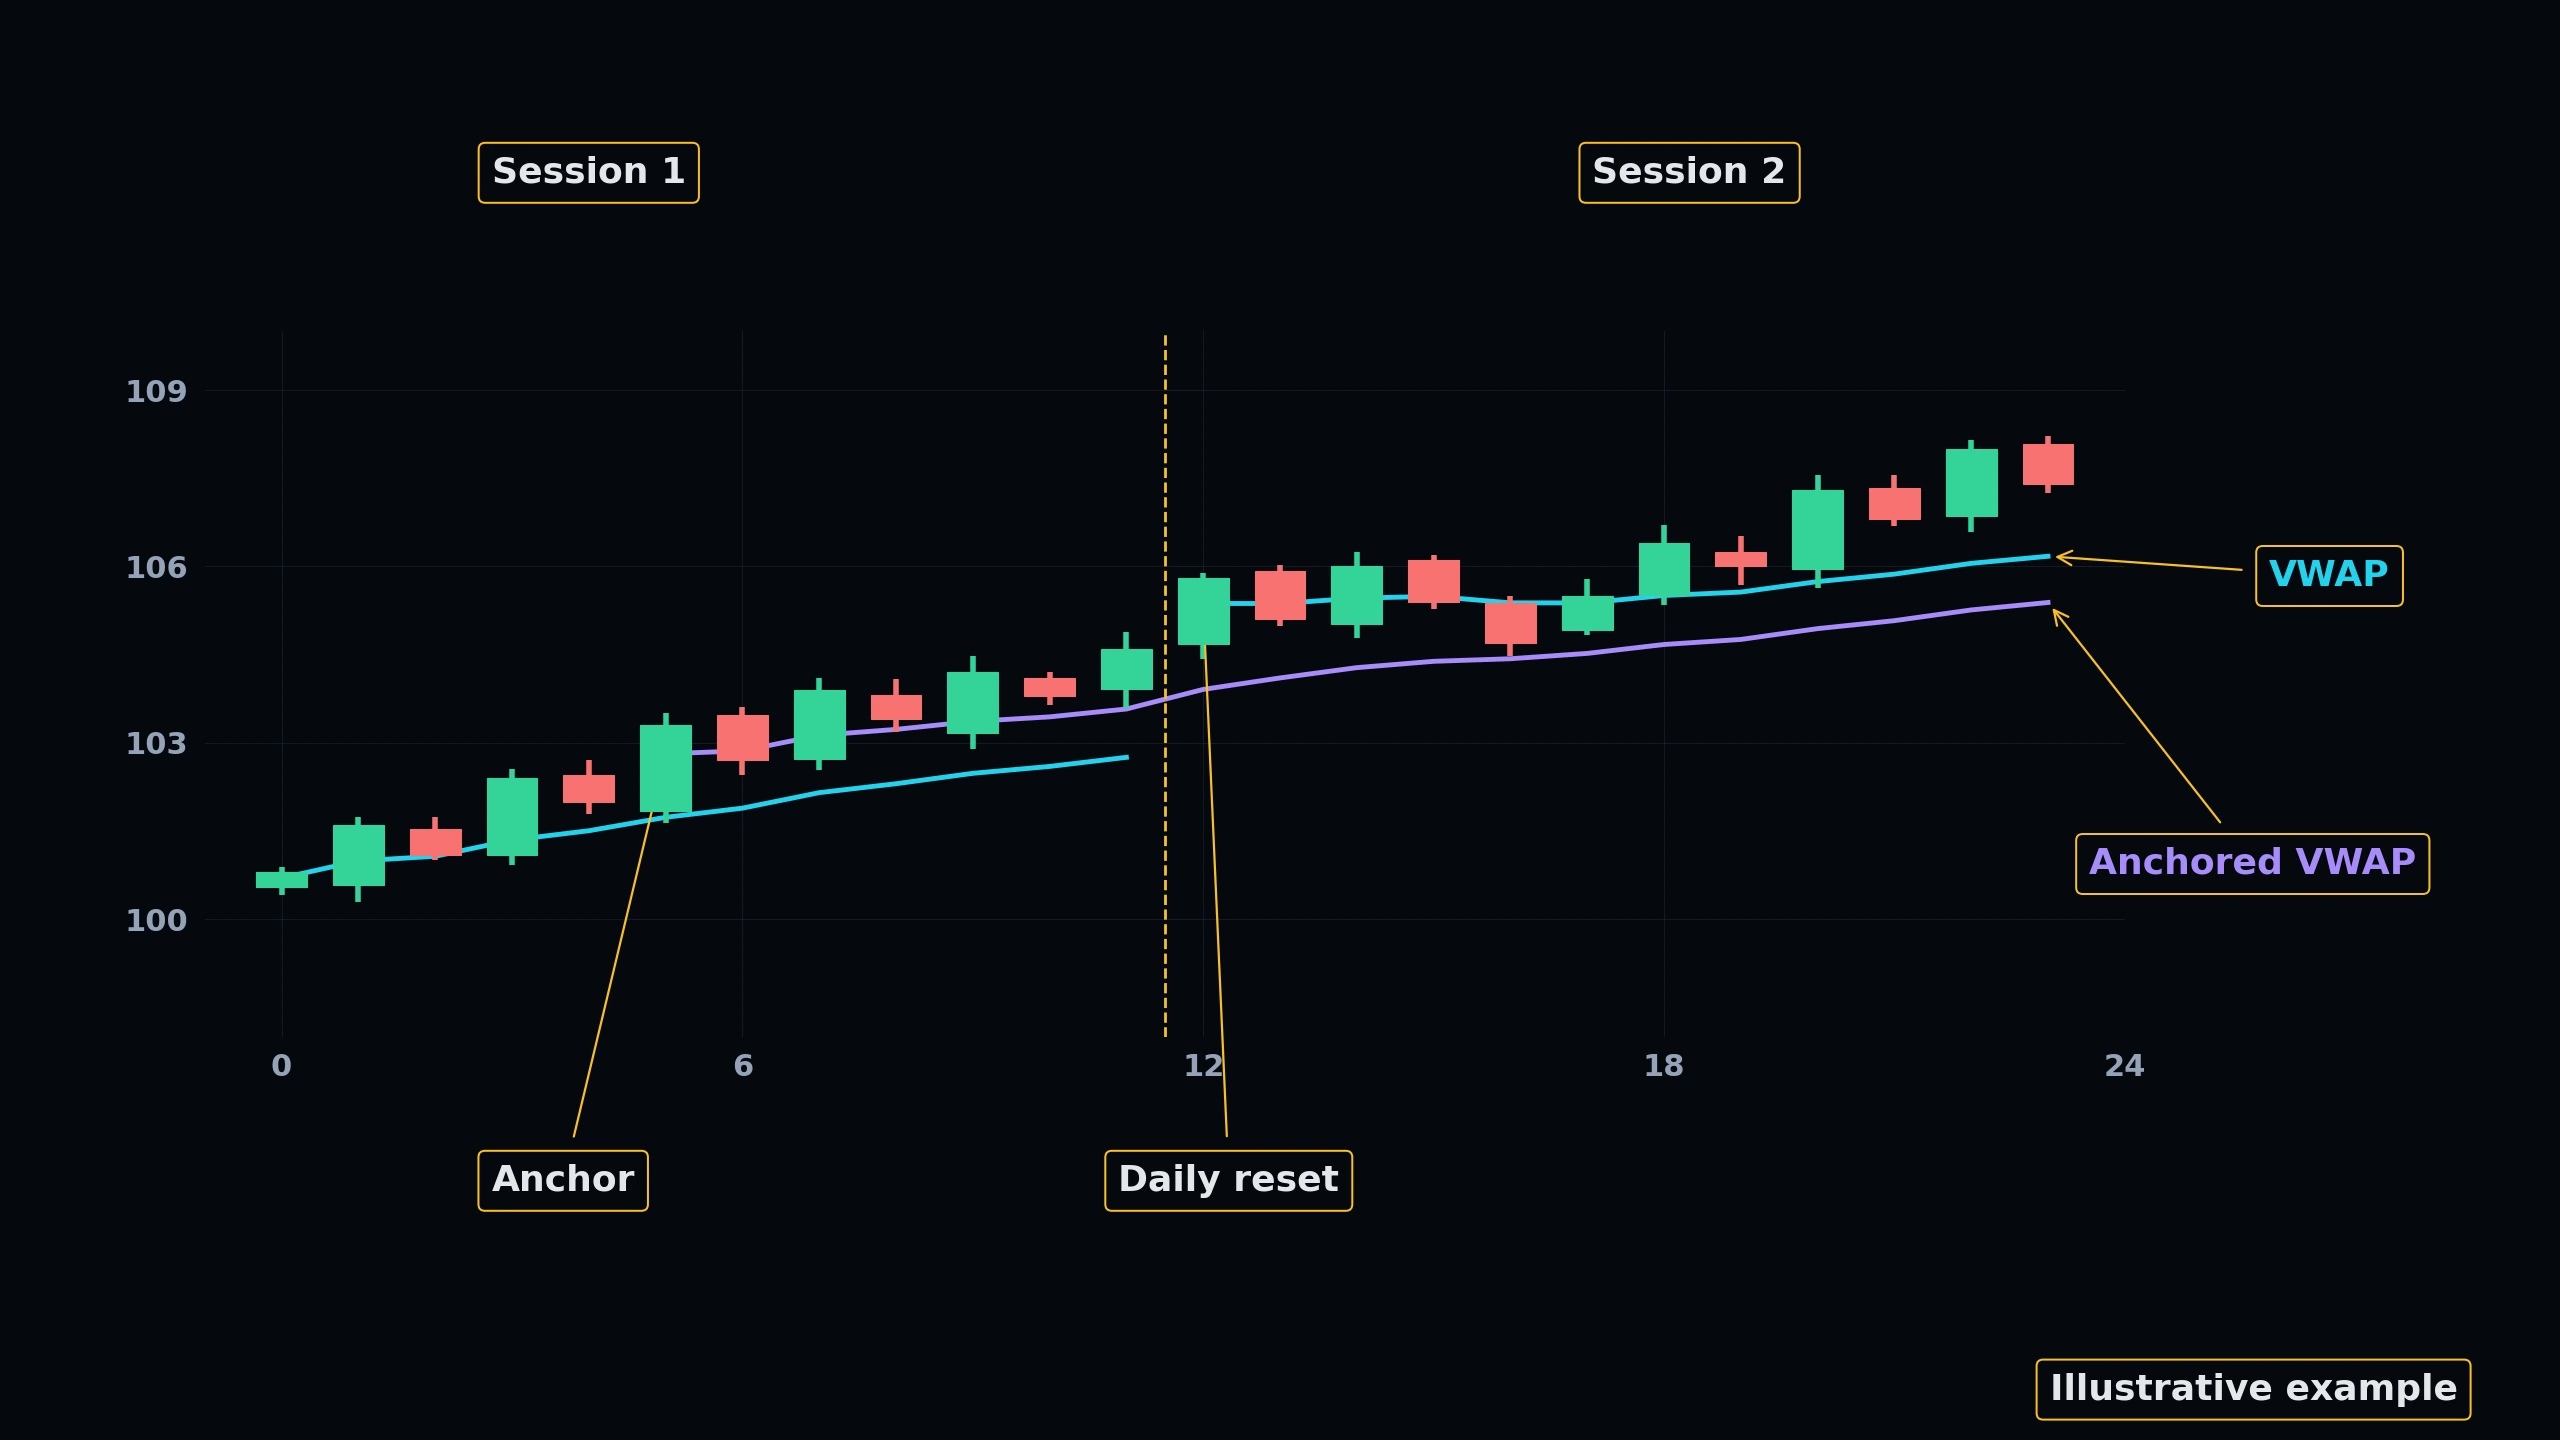
The Volume Weighted Average Price (VWAP) is an intraday calculation that represents the average price an asset has traded at, weighted by both volume and price. It resets at the start of every trading day.
VWAP is the single most important indicator for institutional algorithmic execution. If an algorithm buys below the daily VWAP, it has achieved an 'above average' price. If it buys above, it has paid a premium.
★ Trading Rules: Buy only when price is above VWAP in an uptrend, or pullback to VWAP to buy support. Sell or short when price is below VWAP.
2. Anchored VWAP Mechanics
Unlike standard VWAP which resets daily, Anchored VWAP allows you to 'anchor' the calculation to a specific significant event, such as a major earnings release, a swing low, or a market crash. It calculates volume-weighted fair value from that precise moment forward.
 Click to enlarge
KNOWLEDGE RECONNAISSANCE
Why do institutional algorithms care about the Volume Weighted Average Price (VWAP)?
More lessons in this module
- 8.0: Volume Foundations & Institutional Footprints
- 8.1: Volume Spread Analysis (VSA)
- 8.2: Volume Profile & Point of Control (POC)
- 8.4: Volume-Based Breakouts & Validation
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.