
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Key terms in this lesson
 Click to enlarge
Lesson 3: 5.2: Volatility Crush & Earnings Strategies
Why option buyers lose on earnings even when right, how to read the implied move, and an honest assessment of whether earnings trades are worth taking.
1. The IV Run-Up
In the weeks before a scheduled earnings announcement, implied volatility on that stock rises steadily. The mechanism is straightforward: a known event with an unknown outcome is approaching, demand for options increases, and prices rise.
Typical pattern on a stock with normal IV around 30%:
• 3 weeks before earnings: IV around 32%
• 1 week before: IV around 40%
• Day before: IV around 55%
• Morning after: IV back to roughly 30%
That final line is the entire phenomenon. The elevated volatility does not decay gradually — it collapses within minutes of the announcement, because the uncertainty it was pricing has resolved.
★ Core Fact: IV crush is not a market malfunction or a trap set by institutions. It is the correct repricing of an option once the event it was pricing has occurred.
 Click to enlarge
2. Why Buyers Lose While Being Right
This is the mechanic that produces the most confused losses in options trading.
Worked example: XYZ trades at $100 the day before earnings. IV is 55%. You buy the $100 call, 30 days out, for $6.00.
Earnings are strong. The stock opens at $106 — a 6% move in your favour.
• Intrinsic value gained: $6.00 (the stock is $6 above your strike)
• But IV collapses from 55% to 30%. With a vega of roughly 0.11, that 25-point drop removes about $2.75 of premium
• Extrinsic value also fell from time passing and from the option now being ITM
• Net result: the call is worth roughly $6.80 against the $6.00 you paid — a $80 gain on a 6% favourable move
You forecast direction correctly, the stock moved substantially your way, and you earned almost nothing.
⚠️ Risk Warning: Had the stock risen only 2%, to $102, the option would likely be worth less than you paid despite being correct. Buying options into earnings requires the move to exceed what is already priced in — not merely to be in the right direction.
3. Reading the Implied Move
The market publishes its own expectation, and you can extract it from the option chain in seconds.
★ Approximate implied move = ATM straddle price ÷ stock price
Worked example: XYZ at $100. The nearest expiration after earnings shows the $100 call at $4.20 and the $100 put at $4.00.
• Straddle price: $4.20 + $4.00 = $8.20
• Implied move: $8.20 ÷ $100 = 8.2%
The market expects roughly an 8.2% move in either direction. This single number reframes every earnings trade:
• Buying options is profitable only if the stock moves more than 8.2%
• Selling premium is profitable if the stock moves less than 8.2%
★ Practical Guidance: Before any earnings trade, compute the implied move and ask honestly whether you have a reason to expect a larger or smaller move than the market. If you have no such reason, you have no edge and should skip it.
4. Selling Volatility Into Earnings
The opposite approach is to sell elevated premium and profit from the crush. Structurally this has appeal — you are selling something demonstrably overpriced relative to its normal level.
The standard structures are defined-risk: iron condors or credit spreads with short strikes placed outside the implied move.
Worked example: XYZ at $100, implied move 8.2%. You sell an iron condor with short strikes at $110 and $90, roughly at the edges of the expected range, collecting $1.50 on $5-wide wings.
• Maximum profit: $150 if XYZ finishes between $90 and $110
• Maximum loss: $350
• The stock must exceed the implied move for you to lose
The catch: a single earnings gap can produce a maximum loss that consumes several trades' worth of profit, and gaps are exactly what earnings produce.
⚠️ Risk Warning: Never sell undefined-risk premium into earnings. A naked short put on a stock that gaps down 30% on a guidance cut creates losses far beyond anything the premium justified. If you trade earnings at all, trade defined risk exclusively.
5. An Honest Assessment
This section is the one most courses will not write.
Earnings trades are close to a coin flip with a fee attached. The implied move is generally a reasonable estimate of the actual move — that is what makes it the market price. Options are at their most expensive, spreads widen, and the outcome resolves in a single unpredictable jump.
For a trader with genuine informational edge — deep knowledge of a specific company, a well-tested statistical pattern — earnings can be tradeable. For everyone else, they are an expensive way to gamble while feeling analytical.
★ Practical Guidance: A defensible default for most traders in this course is to hold no positions through earnings on individual stocks. Close short premium before the announcement, avoid opening new positions into it, and re-enter afterward when IV has normalized and premium is cheaper.
This is not timidity. Choosing not to trade a situation where you have no edge is the same discipline as declining a cash-secured put at IV Rank 15.
6. Try It in Signal Desk
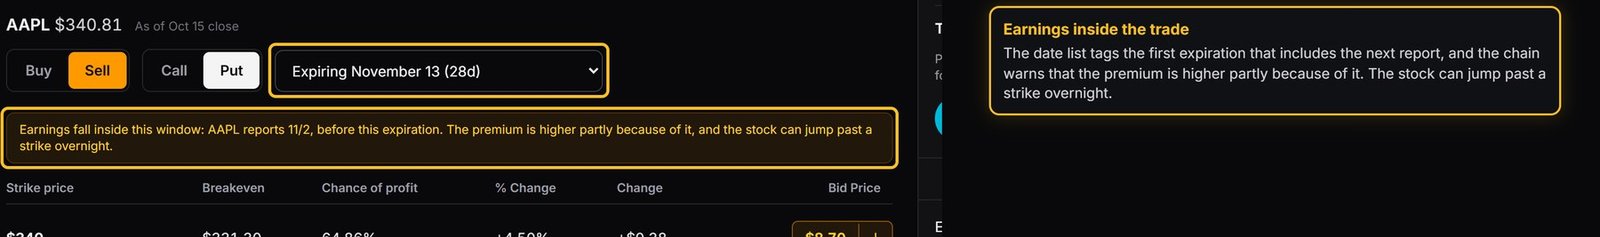
Find a company reporting earnings within the next two weeks; Signal Desk tags the first expiration after the report on the chain, and Stock Research shows the next earnings date. Locate that expiration and compute the implied move with the straddle formula.
Build a long straddle from "Auto-fill a strategy" at the at-the-money strike for that date. Its total cost divided by the stock price is a quick read of the move the market expects. Write that percentage down. Then wait for the announcement and record the actual move.
Repeat this for five companies without trading any of them. You are building a personal record of how often the implied move over- or under-estimates reality. That evidence is worth more than any rule of thumb, and it costs nothing to collect.
See it in Signal Desk
Signal Desk marks the dates that include earnings and builds the straddle you need to read the implied move (members see live quotes).
- 1
Open Stock Research for a ticker and read the "Next earnings" date in the header.
- 2
Open Options and load the same ticker. The first expiration that includes the report carries an earnings tag, and the Easy Chain adds a warning that the premium is higher partly because of it.
- 3
Under "Calls and puts together", choose Long straddle. It buys the at-the-money call and put, and the panel shows the total cost.
- 4
Divide that cost by the stock price. A $12 straddle on a $200 stock suggests the market expects roughly a 6% move.
- 5
Open the Trade Check on a trade that spans the report. It flags earnings inside the window so a surprise cannot sneak up on you.
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
What is an 'IV crush'?
The ATM call is $4.20 and the ATM put is $4.00 on a $100 stock. What is the approximate implied move?
Why do directional option buyers often lose on earnings even when the stock moves their way?
The implied move is 8.2%. When does selling premium into earnings profit?
Why should undefined-risk premium never be sold into earnings?
What is the honest default recommendation for most traders regarding earnings?
More lessons in this module
- 5.0: Vertical Spread Architectures
- 5.1: Iron Condors & Butterfly Spreads
- 5.3: Portfolio Risk & Beta-Weighted Delta
- 5.4: Market Maker Hedging & Gamma Exposure
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.