
A hands-on options curriculum covering real trading concepts. Read the lessons, work through examples, and test your knowledge.
OVERALL ACADEMY PROGRESS
Free Lesson
Every lesson is free to read. Subscribe to add Signal Desk, progress tracking, PDF downloads and the lesson tutor.
Lesson 4: 18.4: Capital Adequacy Rules, Basel III/IV, & Risk-Weighted Assets
Deconstruct Basel III/IV capital adequacy, Common Equity Tier 1 (CET1), Risk-Weighted Assets (RWA), and Liquidity Coverage Ratios (LCR).
1. Basel Capital Adequacy Framework
Basel III and IV international banking standards establish strict capital buffer requirements to ensure banking institutions survive severe economic stress.
• Common Equity Tier 1 (CET1): Highest quality loss-absorbing capital (common shares, retained earnings); must equal at least 4.5% of Risk-Weighted Assets (RWA).
• Risk-Weighted Assets (RWA): Adjusts asset values based on underlying credit, market, and operational risk parameters.
★ Liquidity Coverage Ratio (LCR): Requires holding sufficient High-Quality Liquid Assets (HQLA) to withstand a 30-day severe stress scenario.
2. Net Stable Funding Ratio (NSFR) & Leverage Caps
NSFR requires banks to maintain a stable funding profile in relation to the composition of their assets and off-balance sheet activities over a one-year horizon.
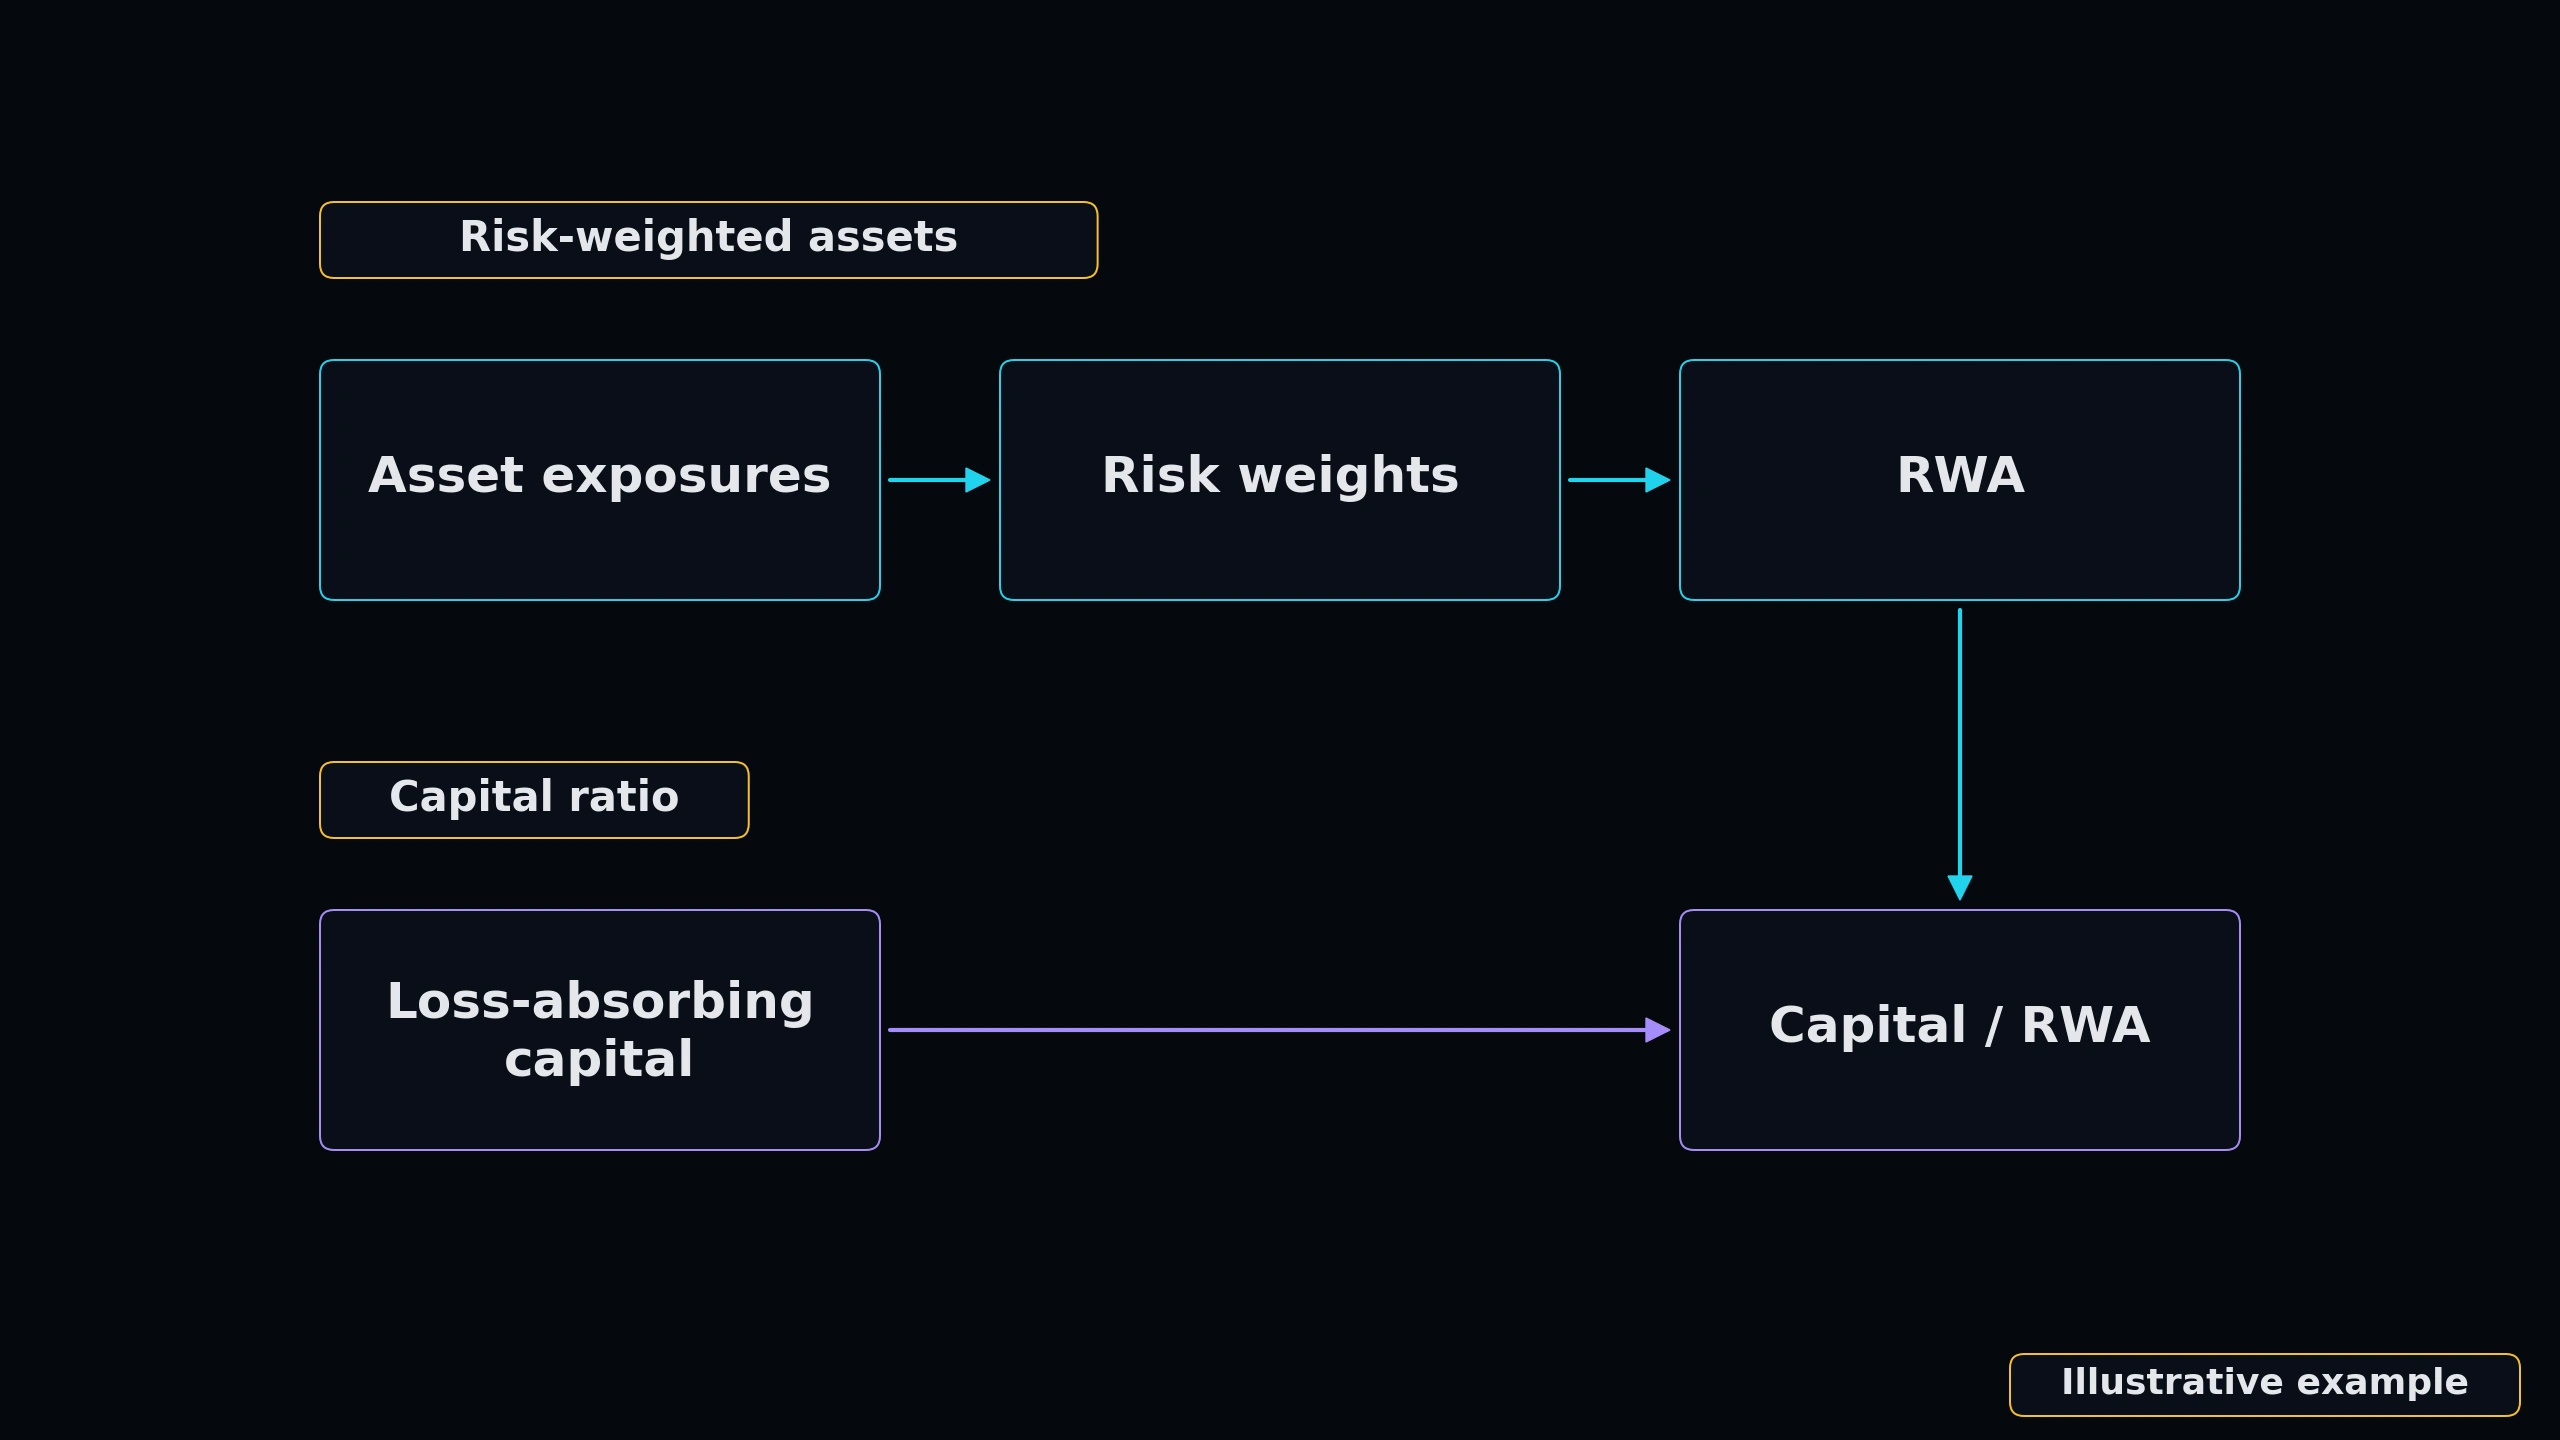 Click to enlarge
IV Crush Scenario Visualizer
Implied Volatility (IV) Crush is the primary account-killer for option buyers after earnings announcements. Play with the controls below to see how option premium collapses depending on Vega.
Scenario Modeling
KNOWLEDGE RECONNAISSANCE
What does the Liquidity Coverage Ratio (LCR) under Basel III mandate for banking institutions?
More lessons in this module
- 18.0: Global Market Regulatory Frameworks (SEC, CFTC, FINRA, ESMA, FCA)
- 18.1: Market Abuse, Insider Trading, & Front-Running Enforcement
- 18.2: Anti-Money Laundering (AML) & Know Your Customer (KYC) Protocols
- 18.3: Trade Reporting, Audit Trails, & CAT (Consolidated Audit Trail)
- 18.5: Best Execution Compliance & MIFID II Unbundling Requirements
- 18.6: Cross-Border Regulatory Jurisdictions & Offshore Tax Frameworks
- 18.7: Algorithmic & HFT Compliance Governance (SEC Rule 15c3-5, MAR)
- 18.8: Regulatory Technology (RegTech) & Automated Surveillance Pipelines
Signal Desk is where you practice this on real stocks: real option chains (about 15 minutes delayed), the Trade Check and a paper-trading account that risks no real money. Join to add it, your progress tracking and PDF downloads.